12.500
%
Negative
127
mm boe
6
%
The prospect of a prolonged conflict with Russia continues to rule out investment, although US-led peace talks are under way. Goodwill towards Ukraine, the US–Ukraine minerals agreement and DFC and UKEF support should drive a rapid reversal once the conflict ends. Outlook maintained because the war continues. Outlook: Negative. Risk premia raised from 10% to 12.5%.
October 8, 2026
Europe - East
mm bbl
bcf
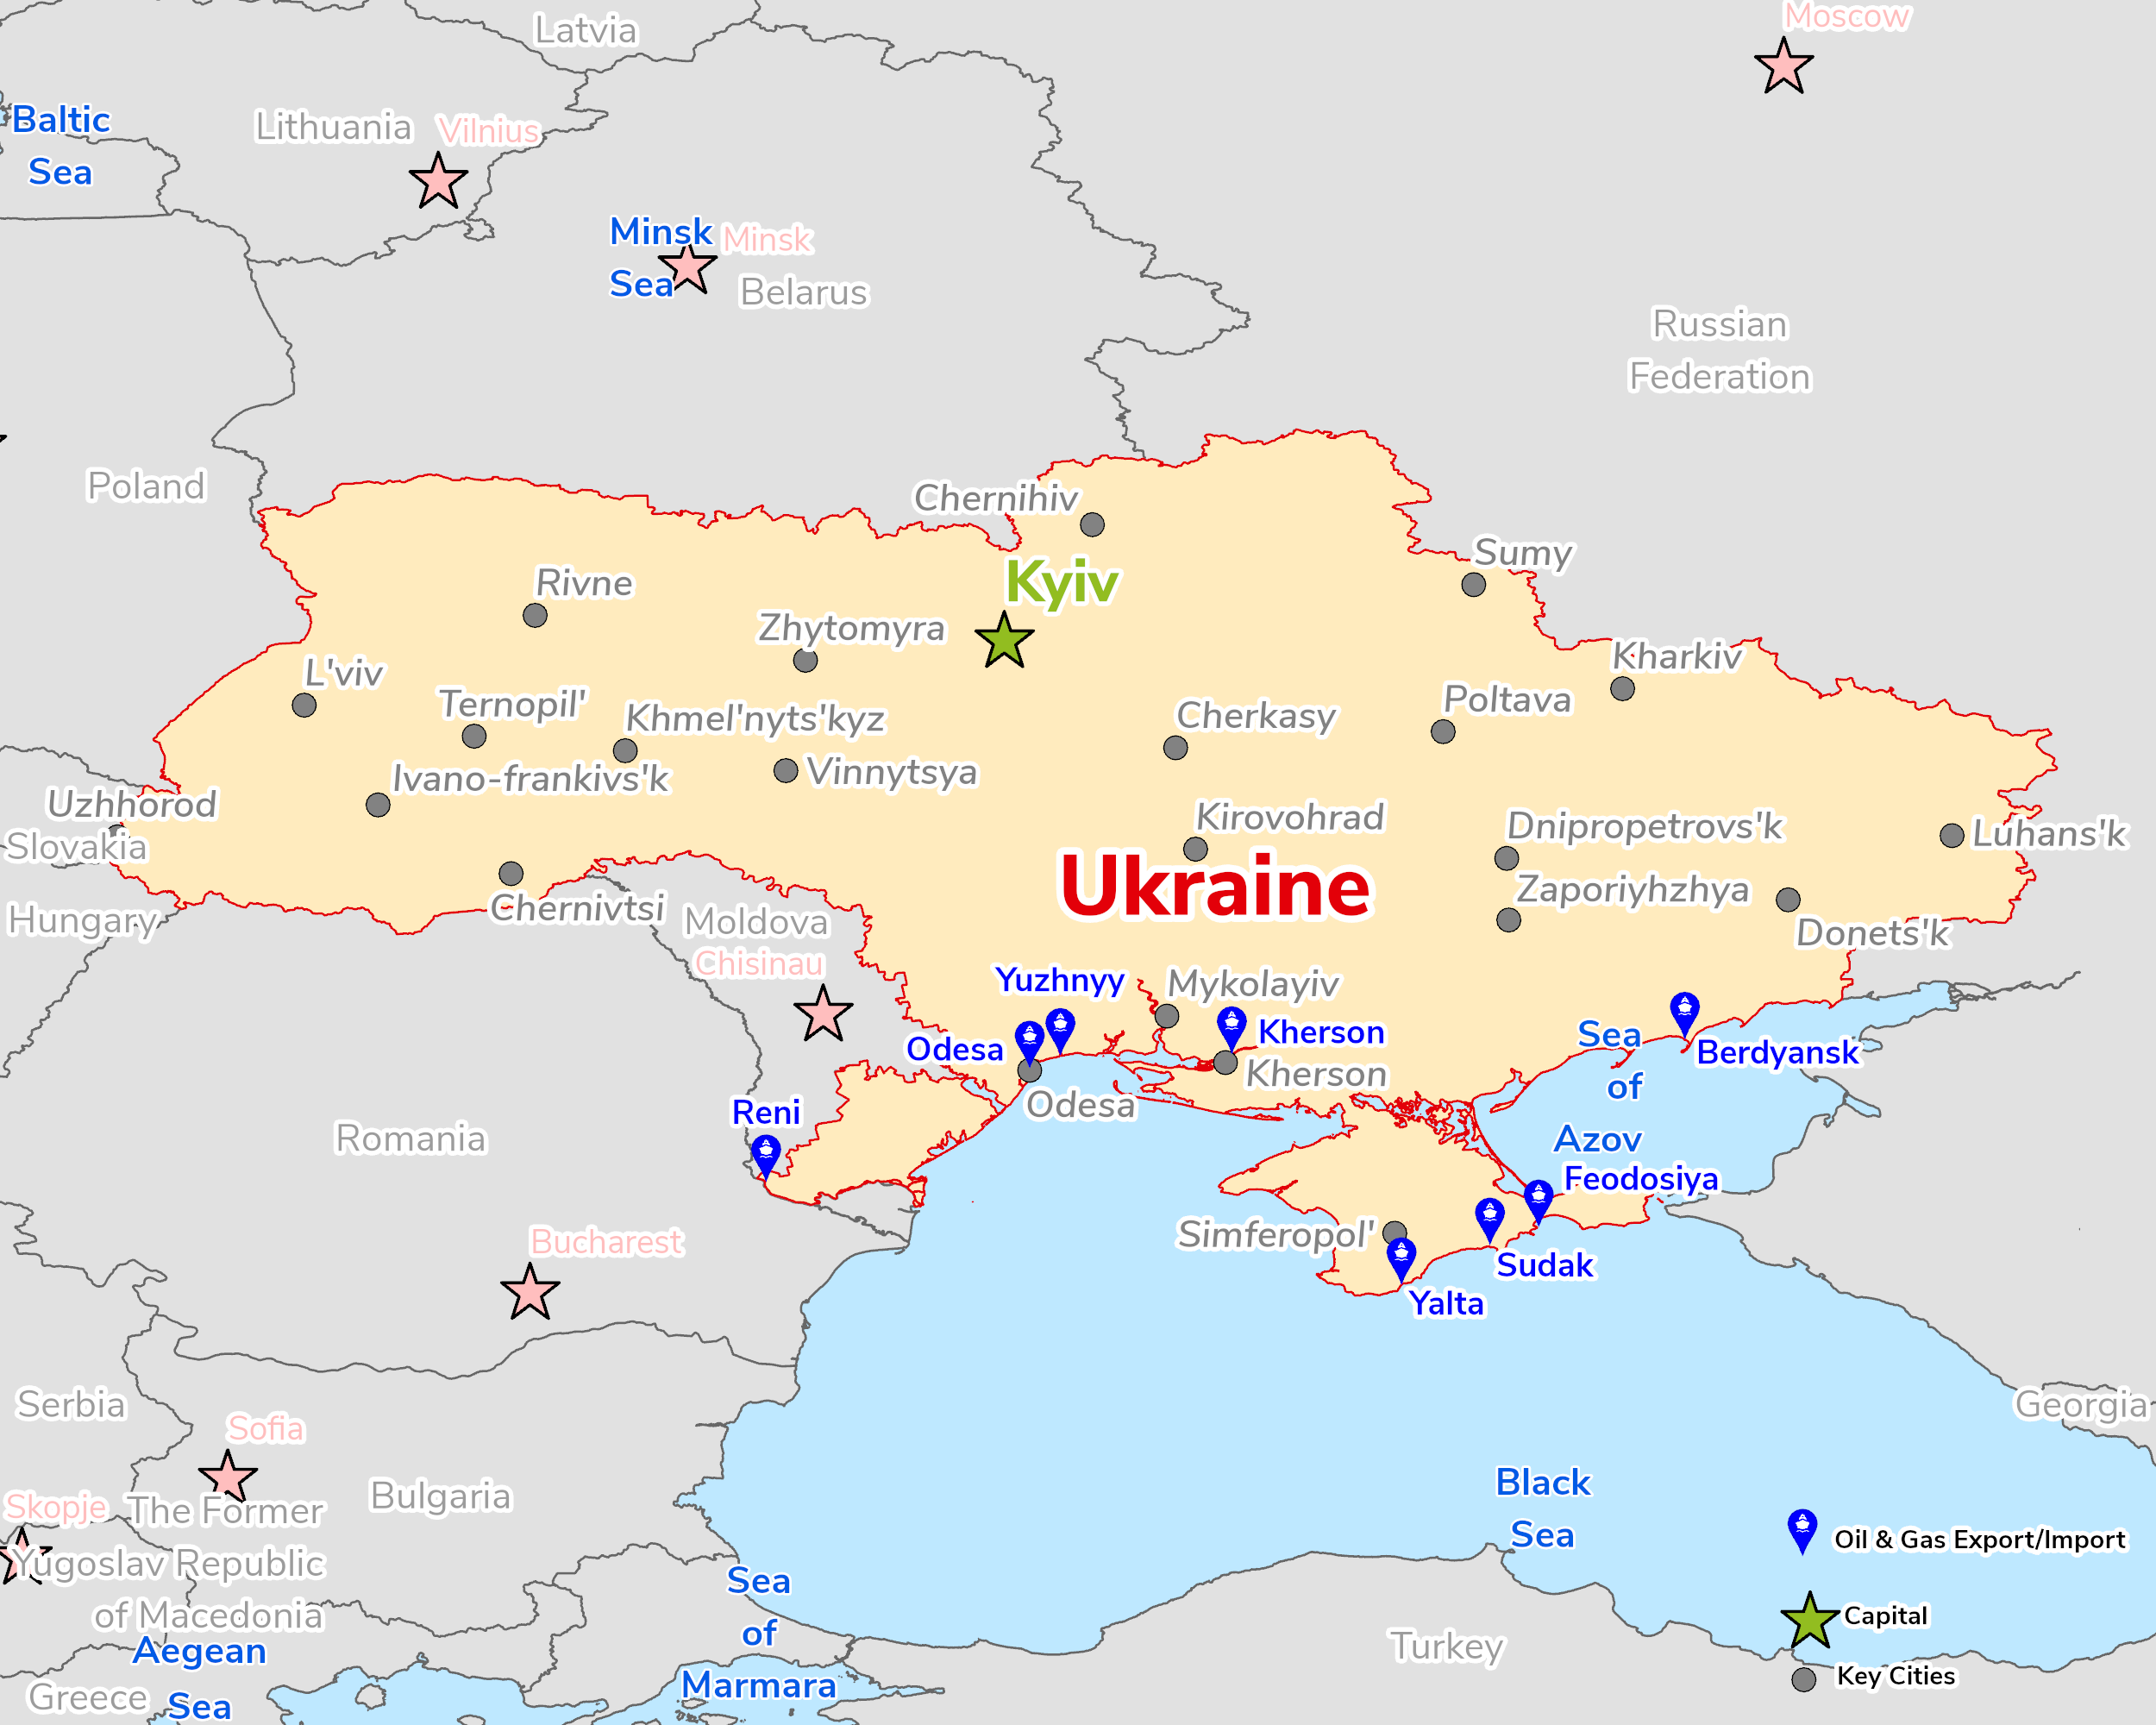
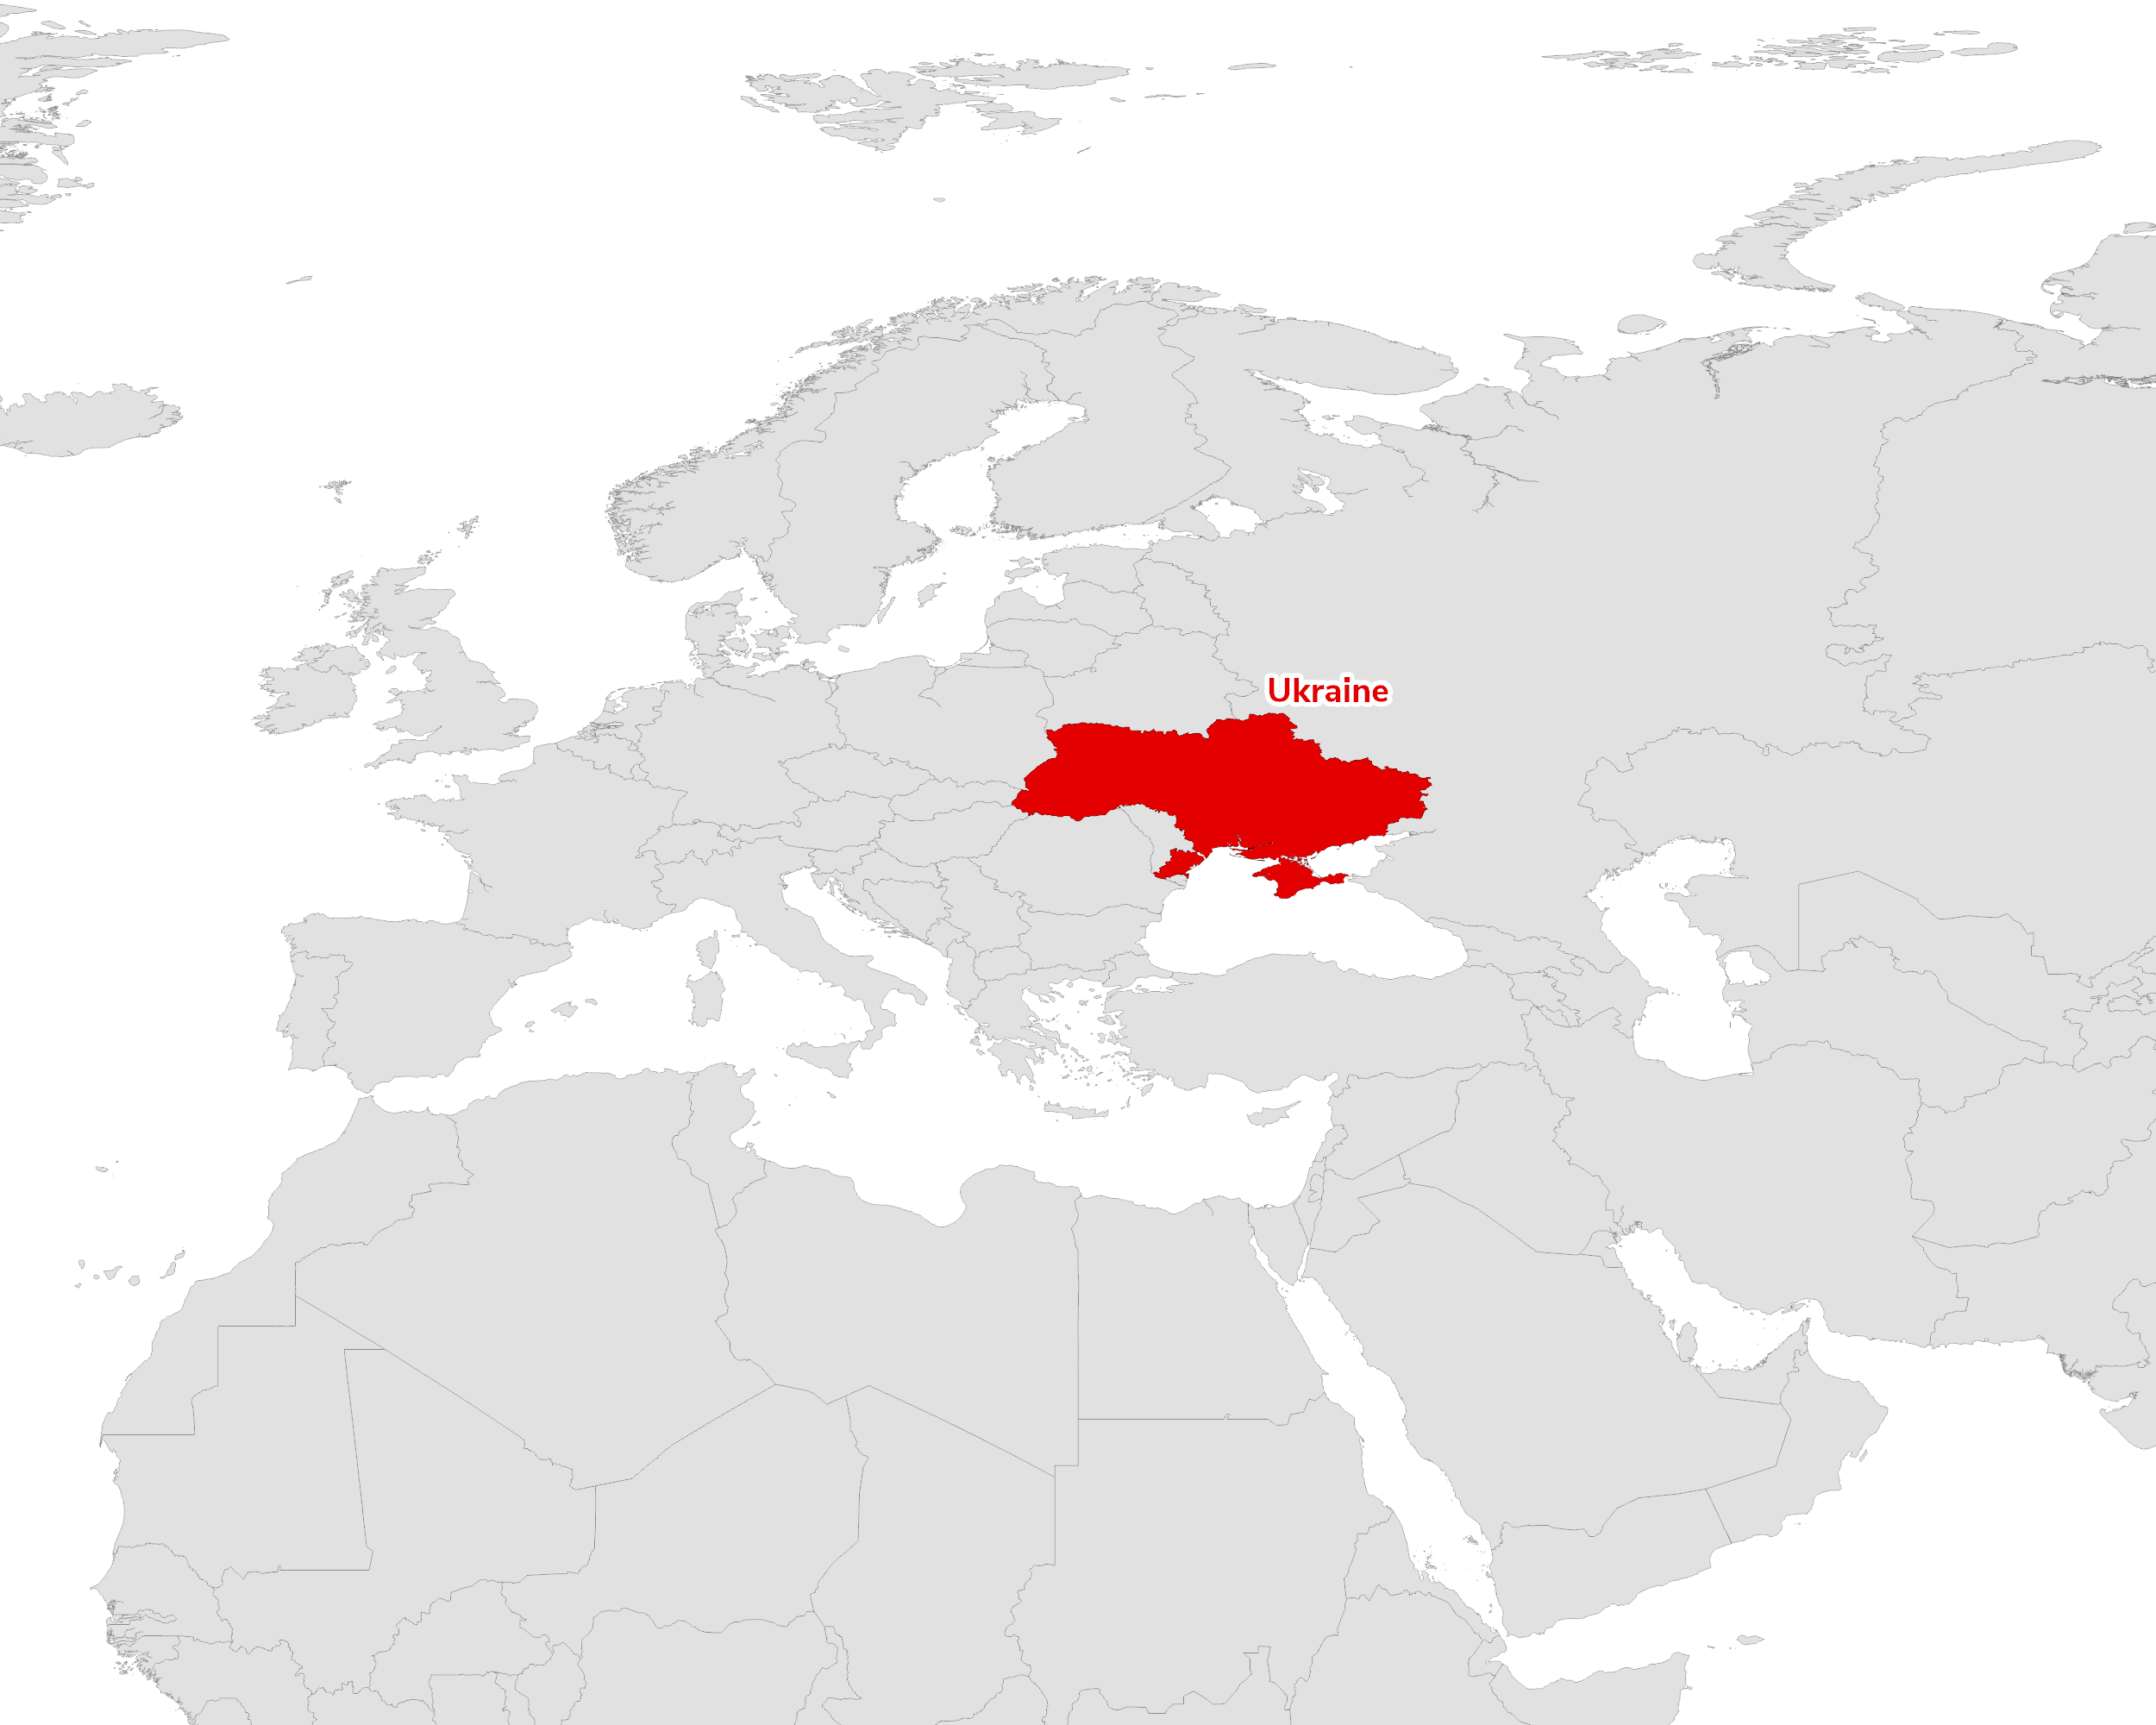
Eastern Europe, bordering the Black Sea, between Poland, Romania, and Moldova in the west and Russia in the east.
Multiple (PSC/Concession)
The royalty/tax system in Ukraine is particularly complex. Various levies are made on production, with rates specified in local currency and differentiated according to the depth of the reservoir and where production is sold. These rates are subject to change annually and, for gas, are tied to regulated prices. As most of the levies are fixed amounts per unit of production, with no deduction for costs, the system is very regressive. When prevailing prices are low, the government generates a significantly higher share of revenue.
Russia's full-scale invasion continues, with US-led peace negotiations under way and a major corruption scandal at Energoatom in late 2025 leading to senior resignations. The FCDO advises against travel to large parts of the country, and US and UK guidance cite war risk, but note reconstruction opportunities supported by DFC and UKEF cover and the 2025 US–Ukraine minerals agreement. The EIA notes that Russian strikes on gas production and power infrastructure have forced higher gas imports. Russian gas transit ended in January 2025, and the Zaporizhzhia nuclear plant remains under Russian occupation.
Source: ESRI, Heritage Index, HMG Foreign & Commonwealth Office, US Department of State, International Trade Administration, International Law Review, Ernst & Young, Wood Makenzie & OGA data.

© 2024 Oil & Gas Advisors Limited
Website by Rugby Web Design

