7.500
%
Neutral
39
mm boe
0
%
The O&G sector has continued to operate despite political upheaval, and Sangomar and Greater Tortue Ahmeyim are now producing. However, the debt crisis following the discovery of hidden liabilities, the suspension of the IMF programme and the government's review of extractive contracts, including its tax dispute with Woodside, have raised contract risk. Outlook amended from Neutral because the debt crisis and contract reviews have raised fiscal and contractual uncertainty. Outlook: Uncertain. Risk premia unchanged at 7.5%.
October 7, 2026
Africa - West
mm bbl
bcf
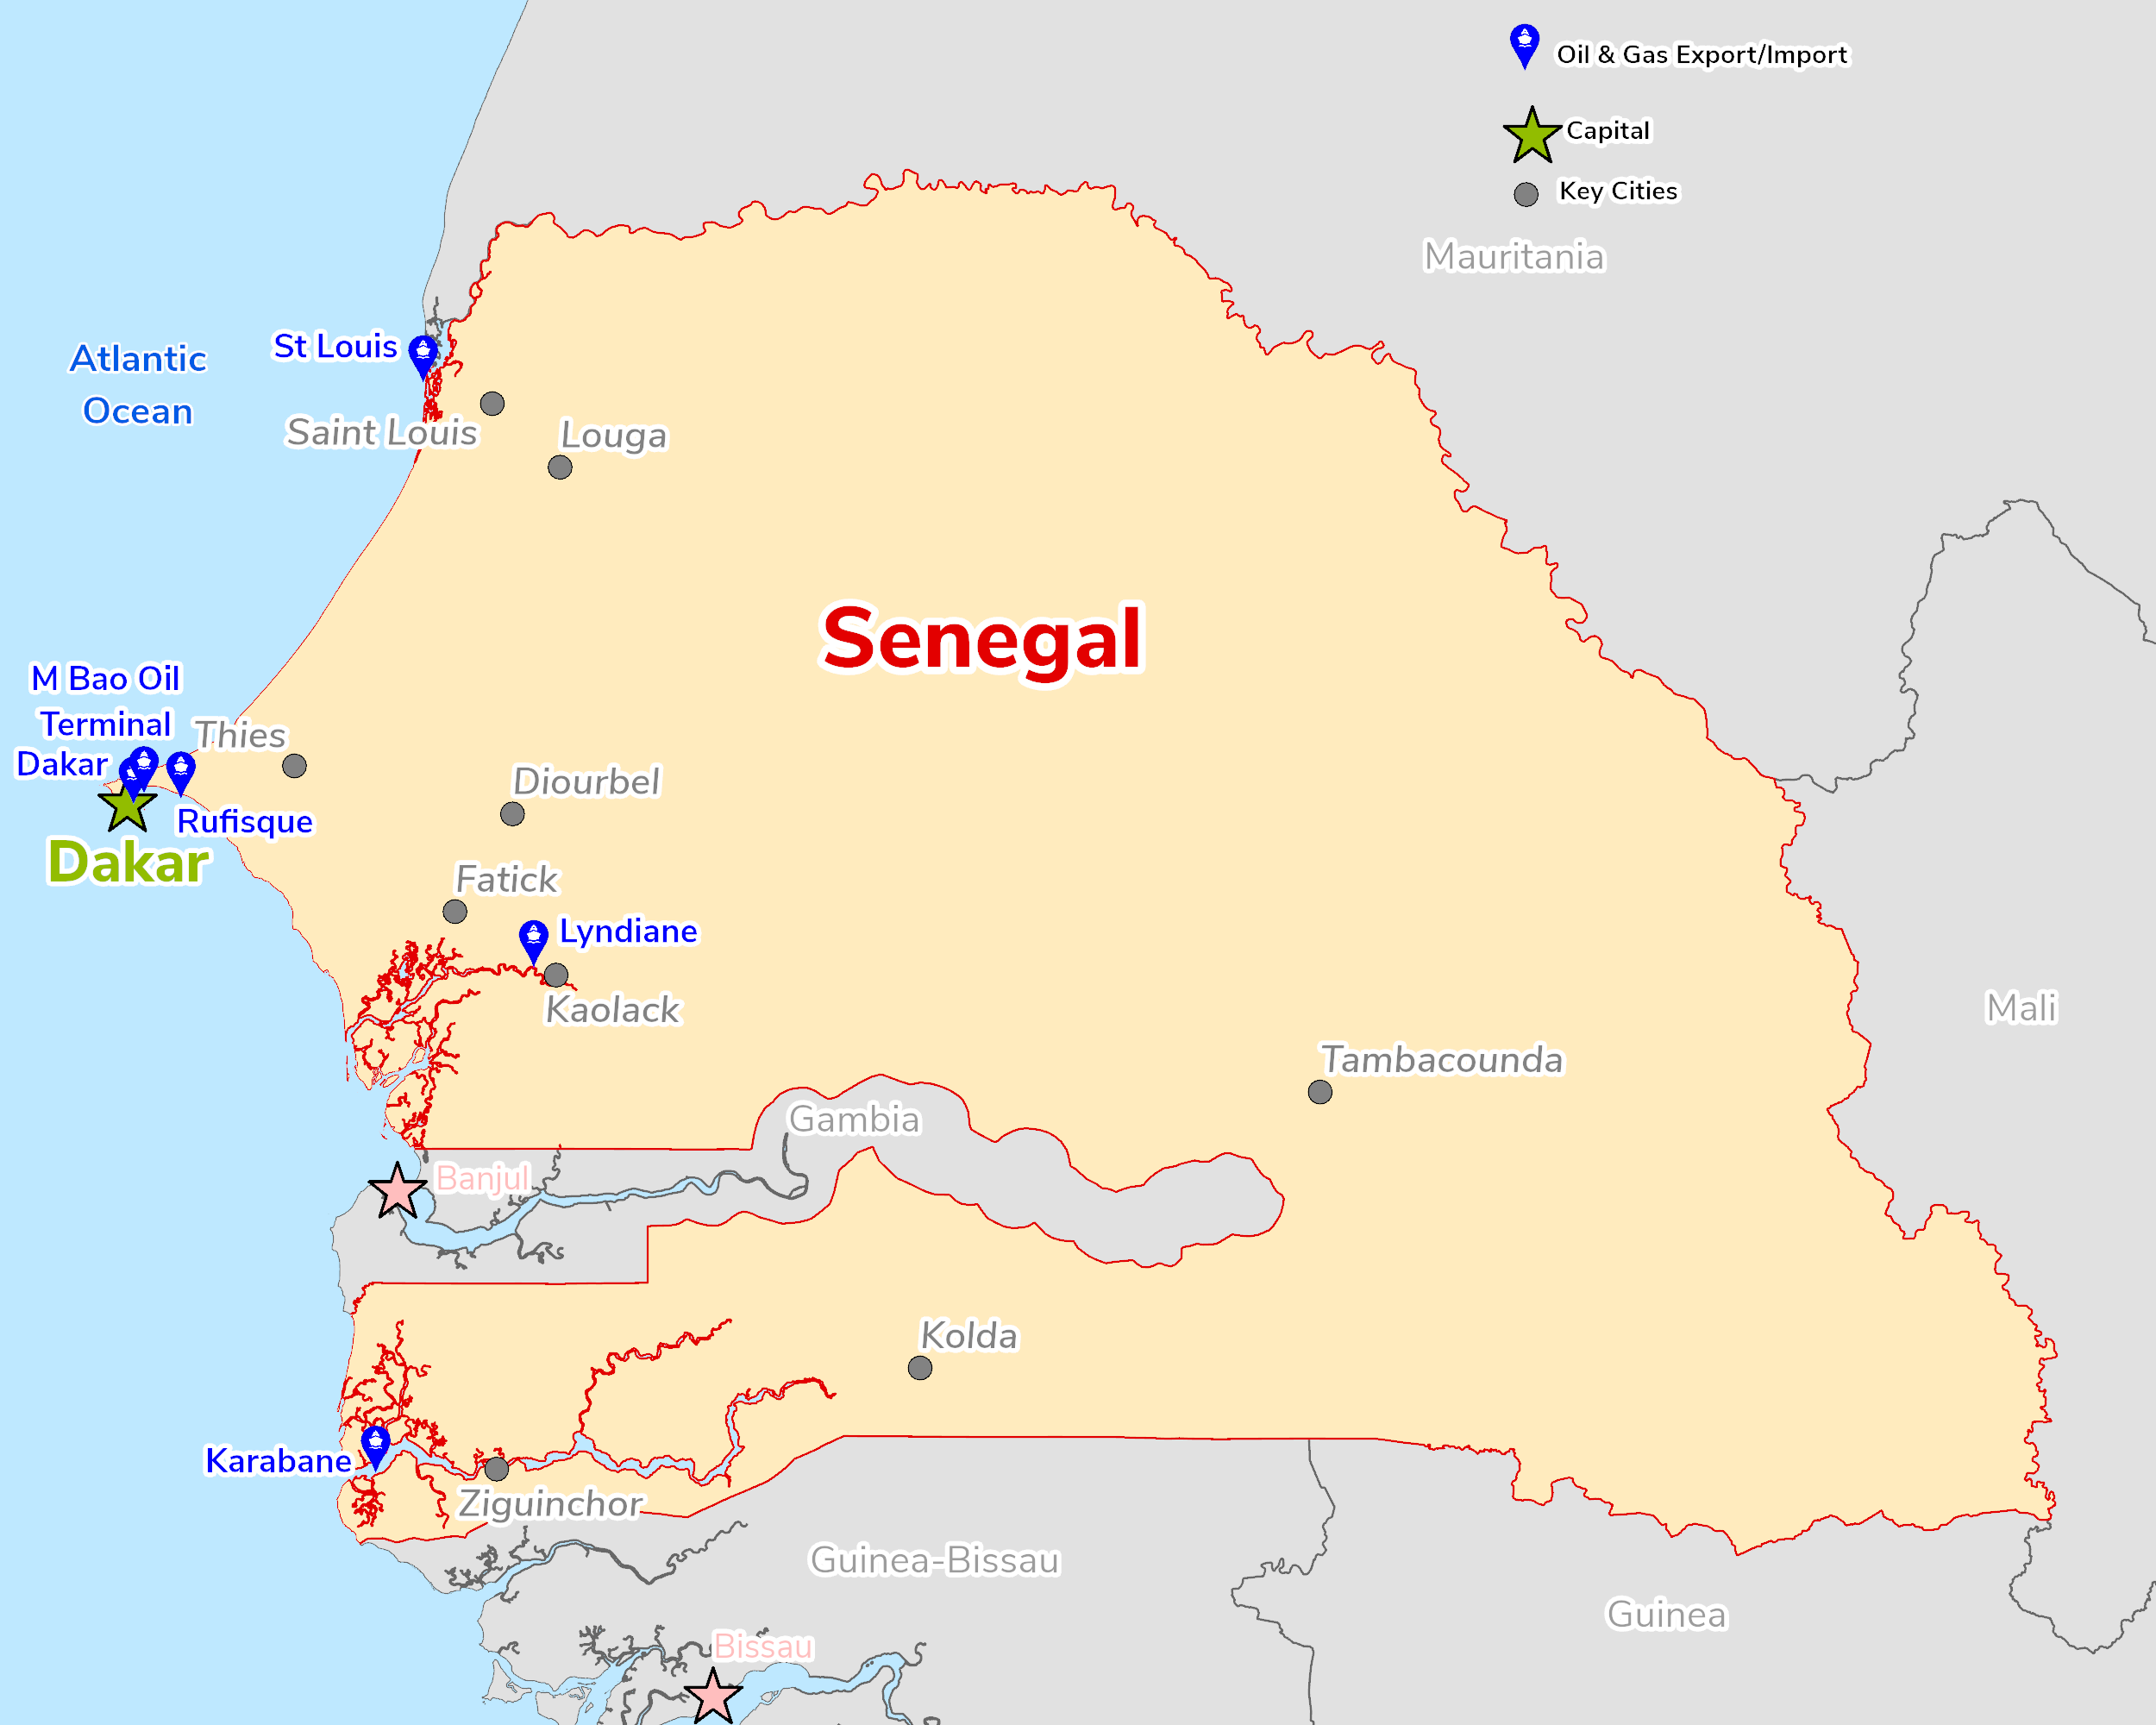
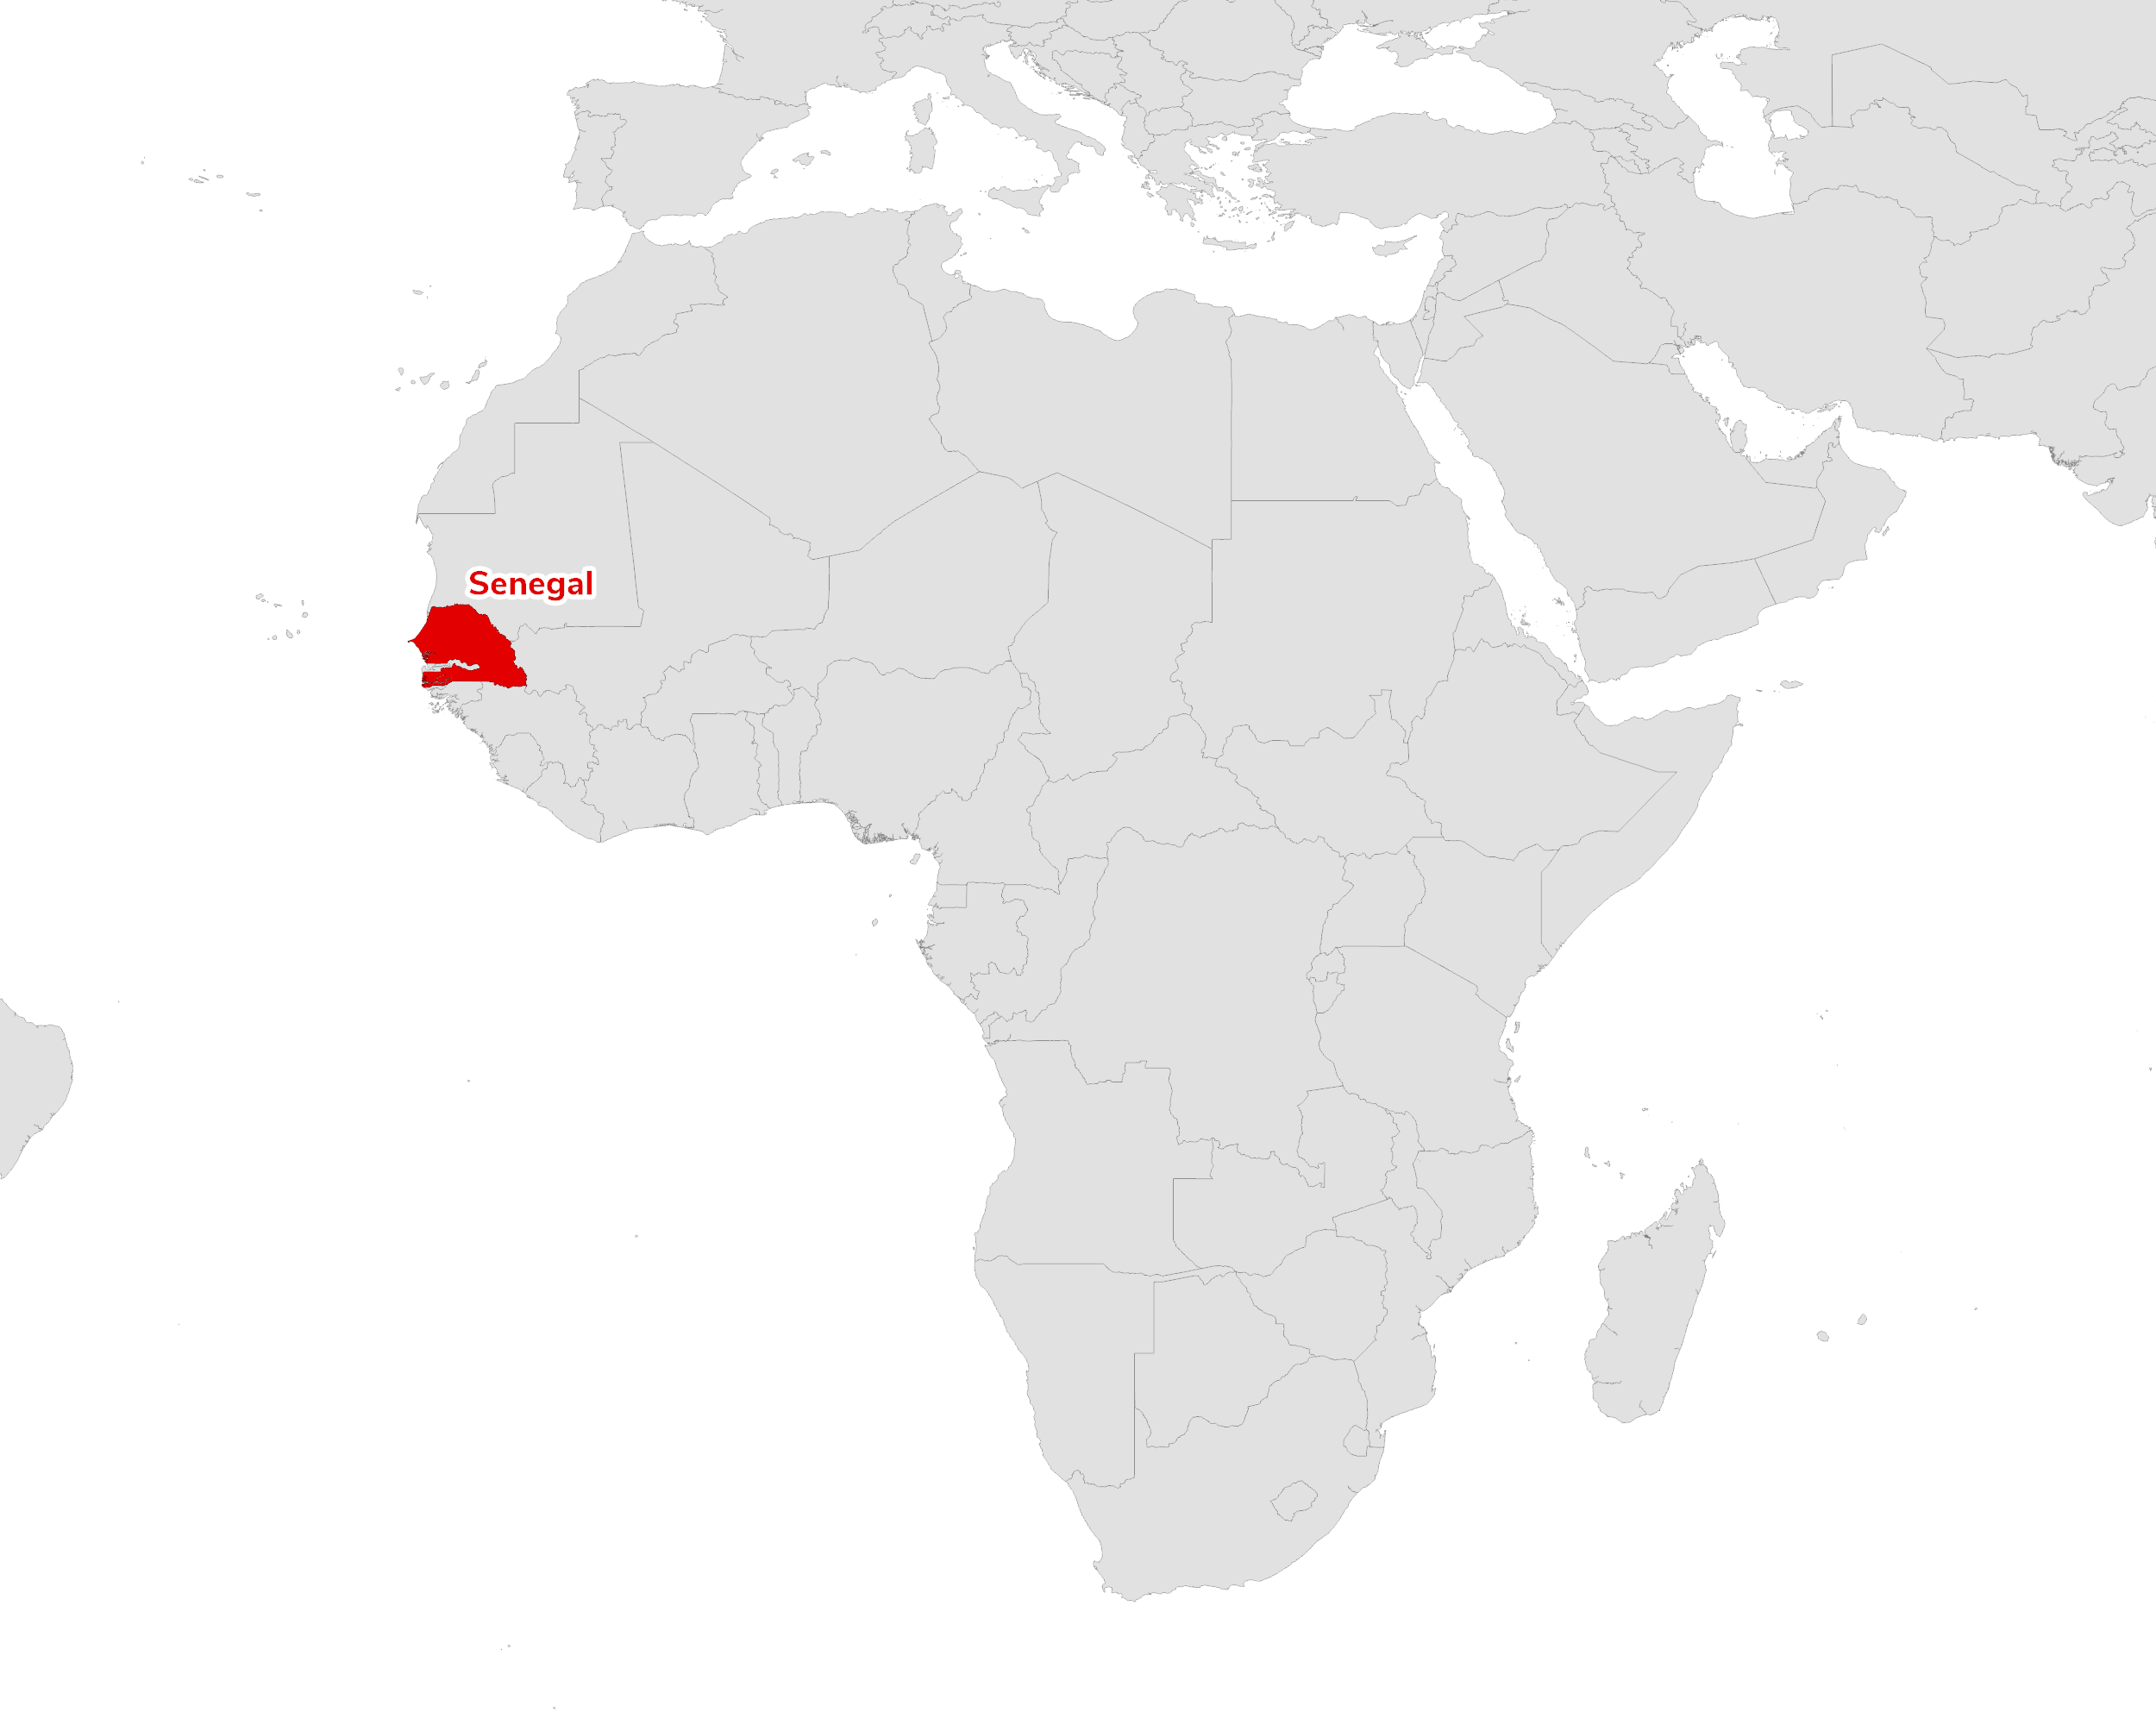
Western Africa, bordering the North Atlantic Ocean, between Guinea-Bissau and Mauritania.
PSC/PSA
Production sharing regime. The 2019 Petroleum Code abolished concessions, so all new upstream rights are awarded as PSCs, with Petrosen holding a carried interest of at least 10% during exploration and an option to increase it on development. Contractors pay royalty, recover costs from a capped share of production and share profit oil on an R-factor scale, with corporate income tax at 30%. The current government has audited existing contracts, including Sangomar and GTA, seeks to renegotiate terms and has pursued tax claims against operators.
President Bassirou Diomaye Faye and Prime Minister Ousmane Sonko face a debt crisis after an audit revealed large hidden liabilities, suspending the IMF programme and triggering downgrades. US and UK guidance cite reform ambitions, but note payment arrears and the government's review of extractive contracts, including a tax dispute with Woodside. The EIA notes that Senegal became a producer in 2024 with Woodside's Sangomar oil field, followed by first LNG from Greater Tortue Ahmeyim with Mauritania in 2025.
Source: ESRI, Heritage Index, HMG Foreign & Commonwealth Office, US Department of State, International Trade Administration, International Law Review, Ernst & Young, Wood Makenzie & OGA data.

© 2024 Oil & Gas Advisors Limited
Website by Rugby Web Design