7.500
%
Negative
146
mm boe
11
%
Endemic corruption and nationalisation left the investment environment poor, and production has collapsed. The election of Rodrigo Paz in October 2025 marks the long-awaited move away from MAS socialism, with fuel-subsidy reform and a new hydrocarbons law to attract private investment promised, although delivery and the FX crisis are major tests. Outlook amended from Negative because the change of government marks the turn away from socialism that we set as our trigger. Outlook: Neutral. Risk premia unchanged at 7.5%.
October 7, 2026
Americas - South
mm bbl
bcf
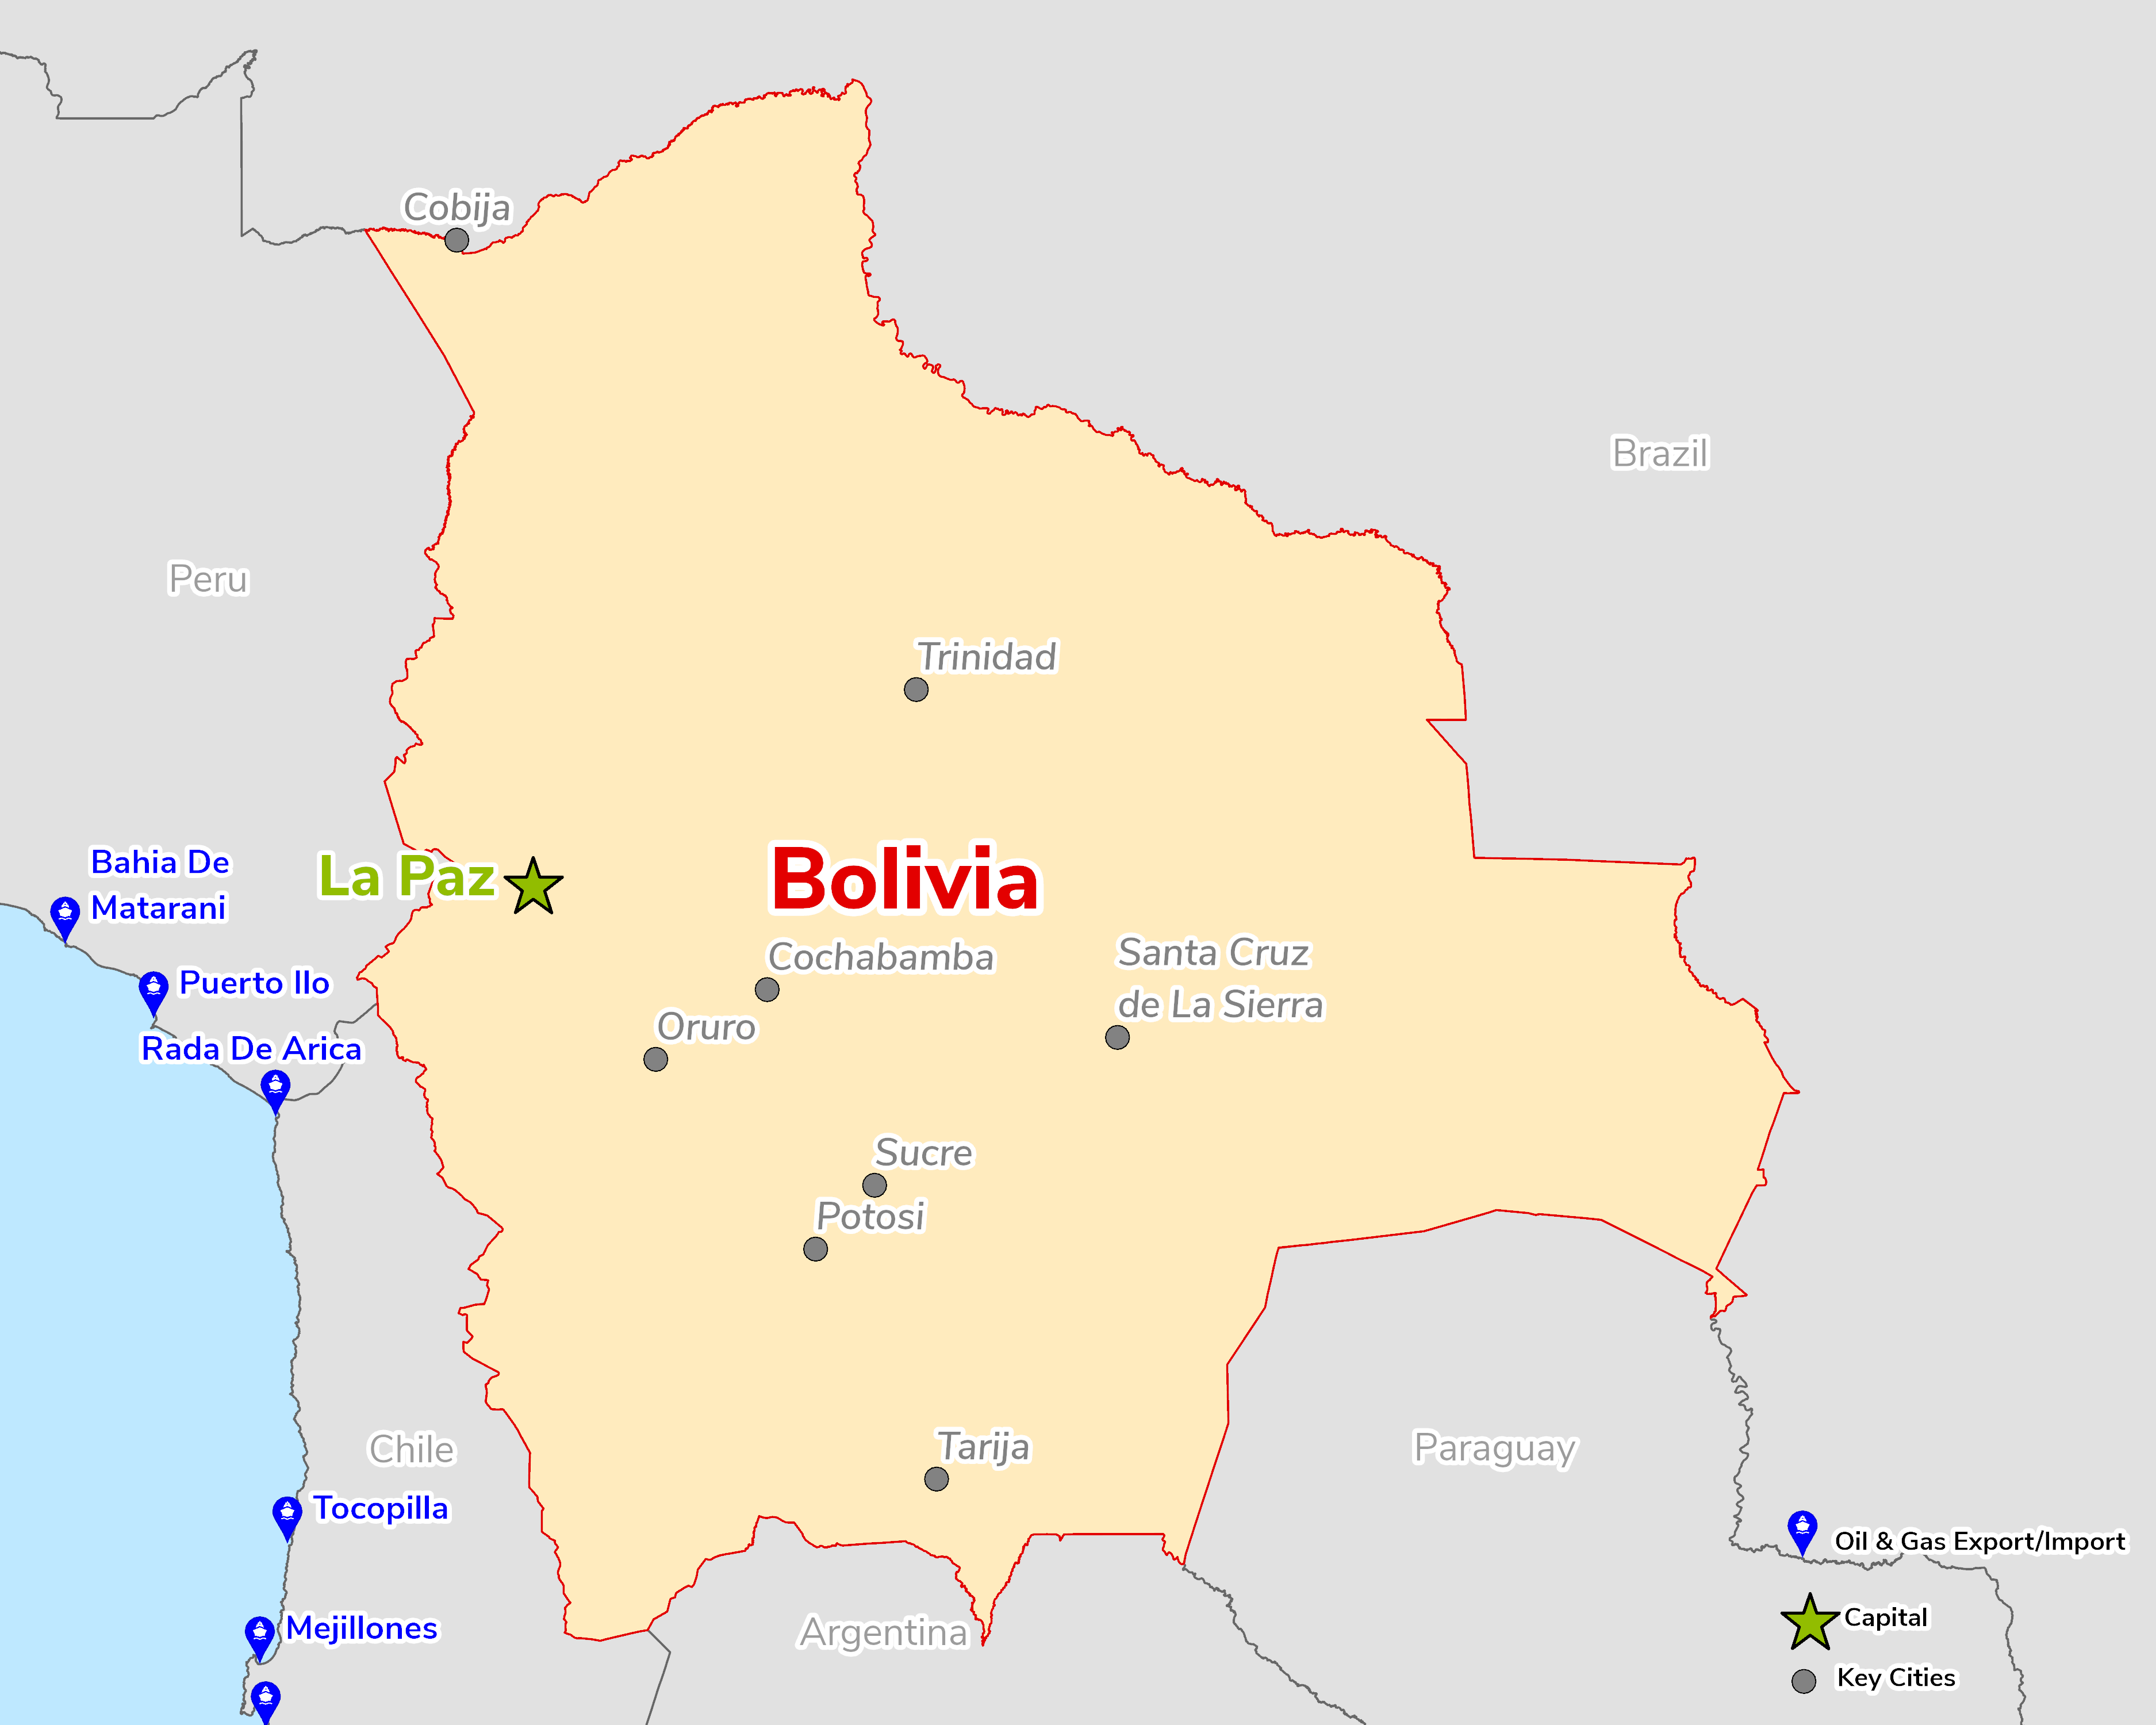
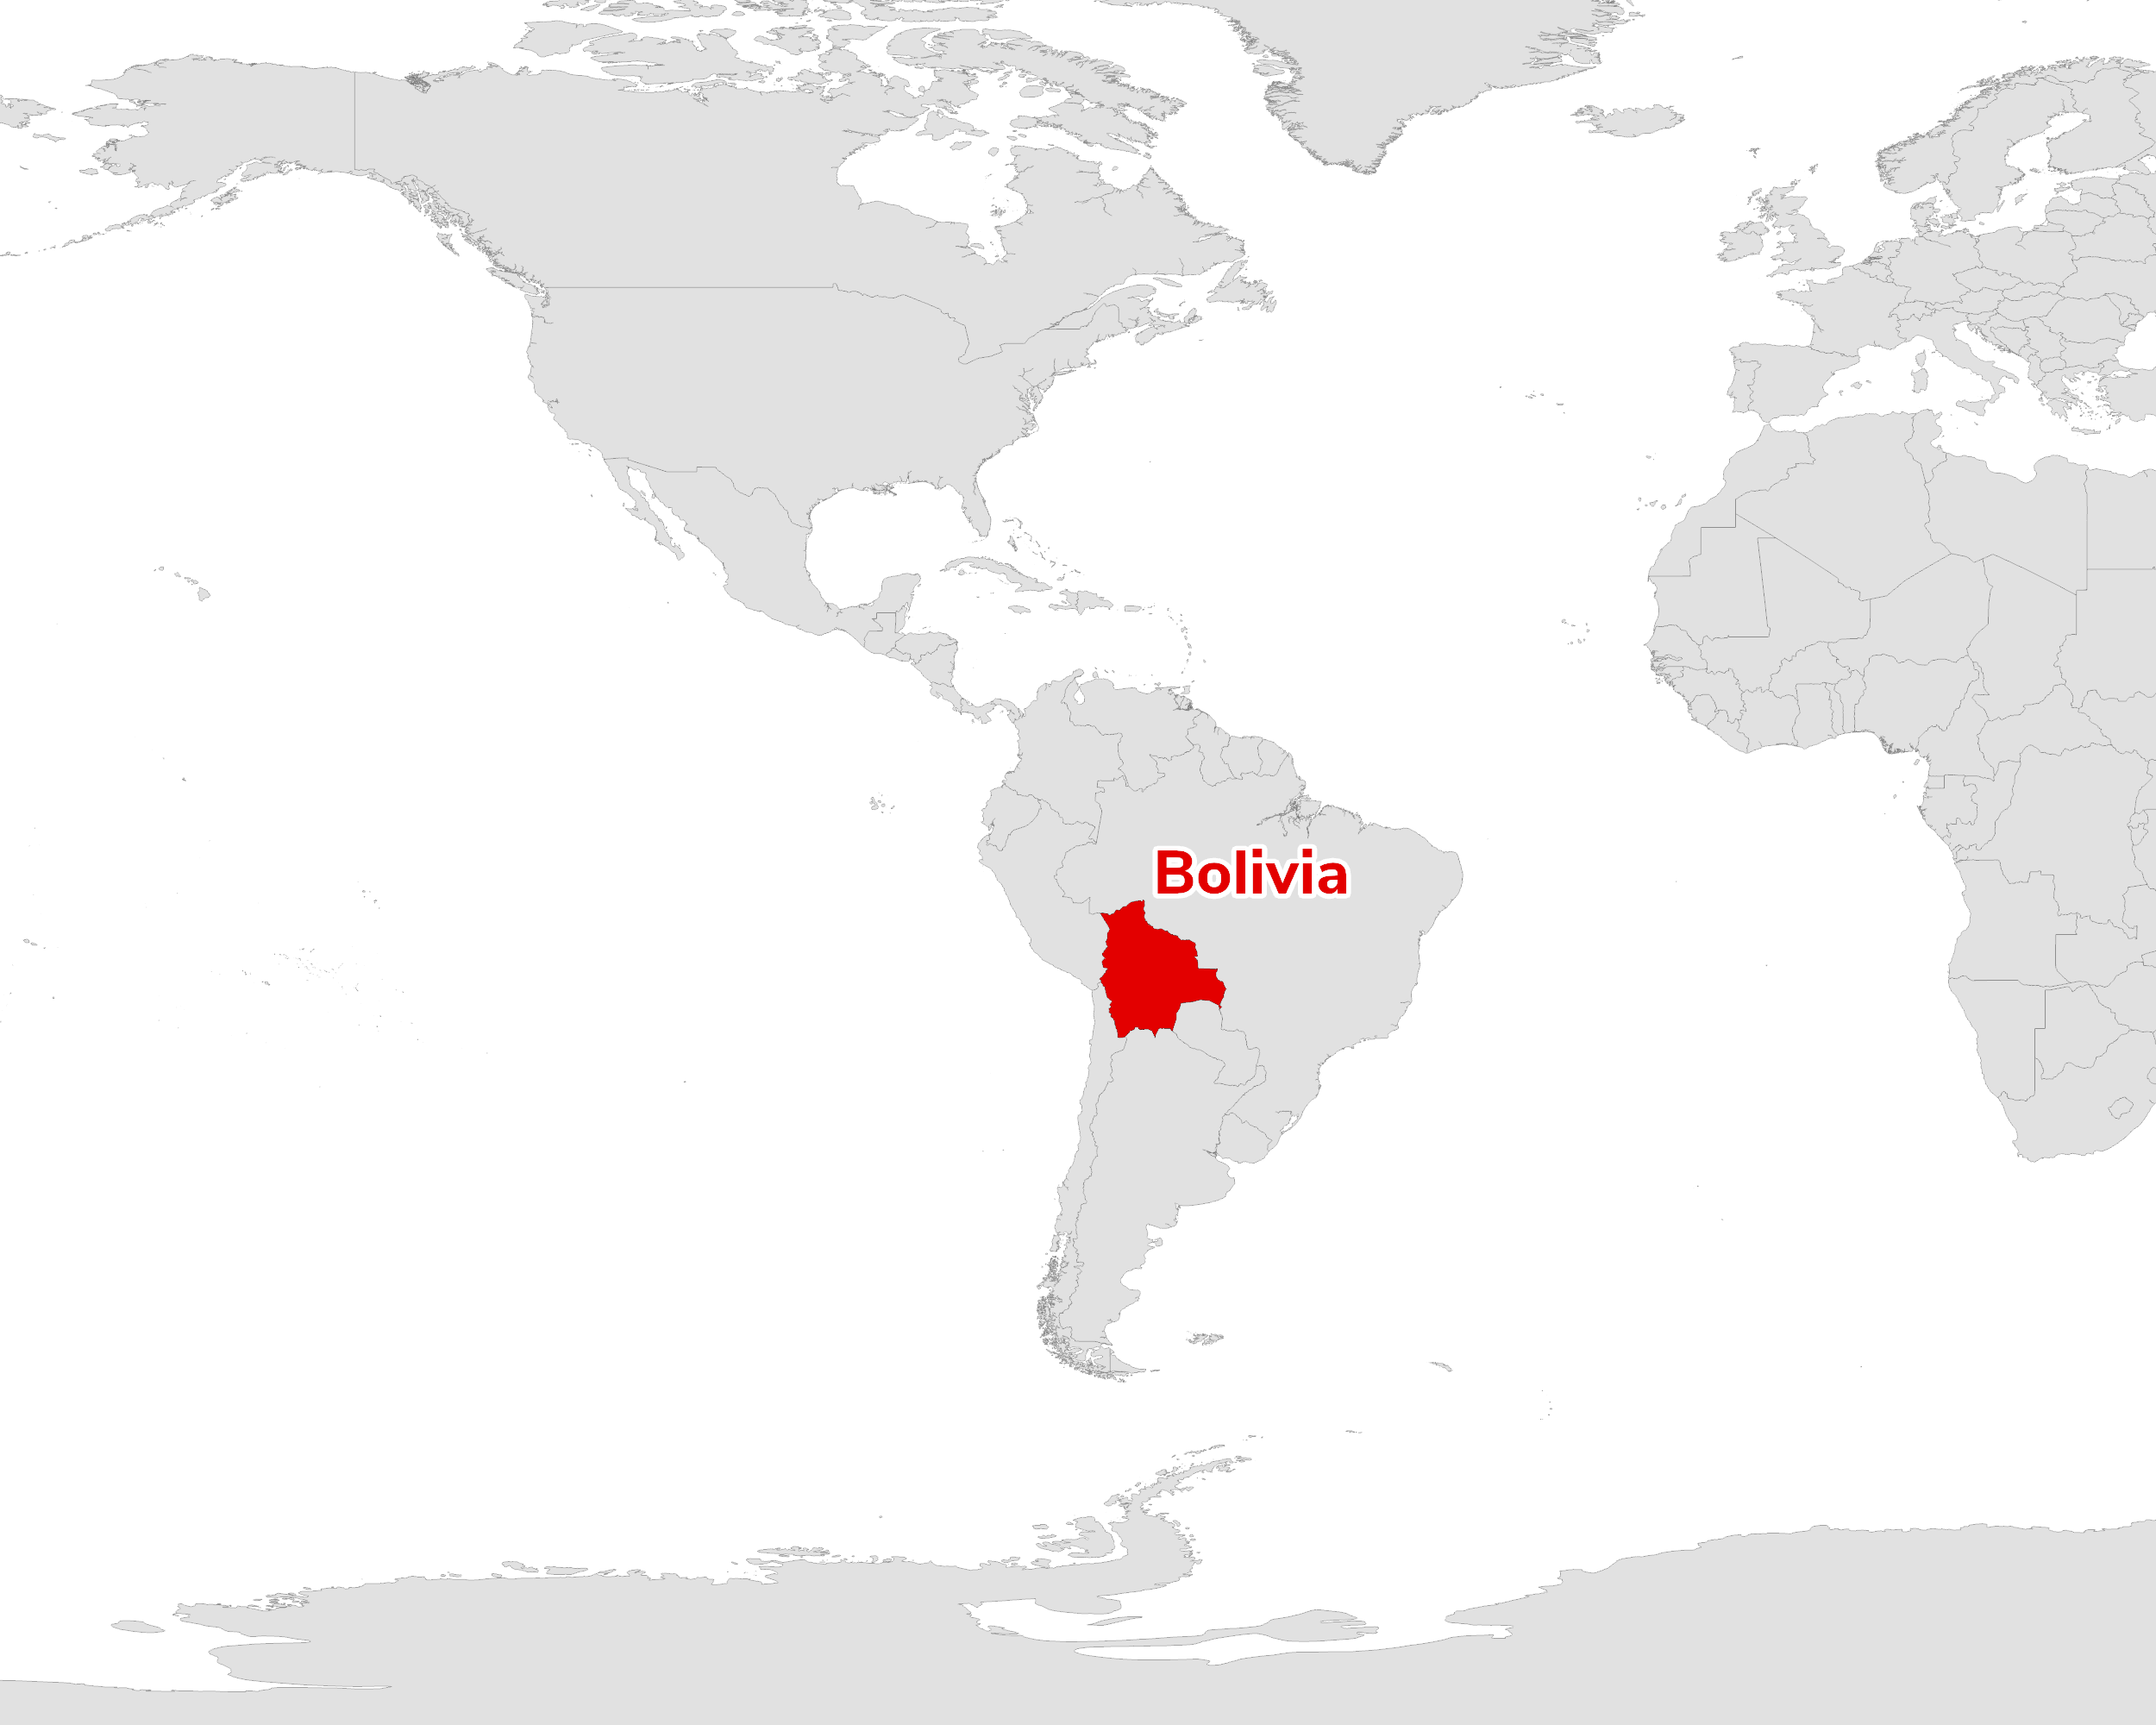
Central South America, southwest of Brazil
Multiple (PSC/Concession)
An 18% royalty and 32% IDH (Direct Tax on Hydrocarbons) applies to each field, creating a combined 50% effective royalty on each field. Cost recovery in any given month is the lower of allowable recoverable costs and the net revenue multiplied by a factor (100% for most fields, certain fields have lower limits). Profit oil splits are on a sliding scale, based on production levels and a so-called B-factor, measuring cumulative revenues and depreciations over cumulative investments and taxes/royalties paid (excluding VAT). Rates vary from field to field, under the principle of increasing government take with increasing project level of payback. Following the profit split, an operator's income (not including cost recovery) is also subject to corporation tax.
Rodrigo Paz won the October 2025 presidential run-off, ending nearly two decades of MAS rule. He inherits an acute FX shortage, fuel shortages, depleted reserves and high subsidy costs. US and UK guidance cite nationalisation risk under the existing hydrocarbons law, state dominance via YPFB, contract insecurity and social unrest. The EIA notes that natural gas output has fallen steeply as mature fields deplete, so that exports to Argentina ceased in 2024 and those to Brazil are shrinking. The new government's openness to private and foreign capital in hydrocarbons and lithium is a key upside risk.
Source: ESRI, Heritage Index, HMG Foreign & Commonwealth Office, US Department of State, International Trade Administration, International Law Review, Ernst & Young, Wood Makenzie & OGA data.

© 2024 Oil & Gas Advisors Limited
Website by Rugby Web Design