3.125
%
Negative
50
mm boe
85
%
Confidence in the government remains low, making only large projects justifiable when the country needs a vibrant E&P sector. Petrobras's licence to drill on the Equatorial Margin and successful permanent-offer rounds are positives, but tax changes and the October 2026 election leave policy direction unresolved. Outlook maintained because we will reassess once the October 2026 election outcome and fiscal direction are clear. Outlook: Negative. Risk premia unchanged at 3.125%.
October 7, 2026
Americas - South
mm bbl
bcf
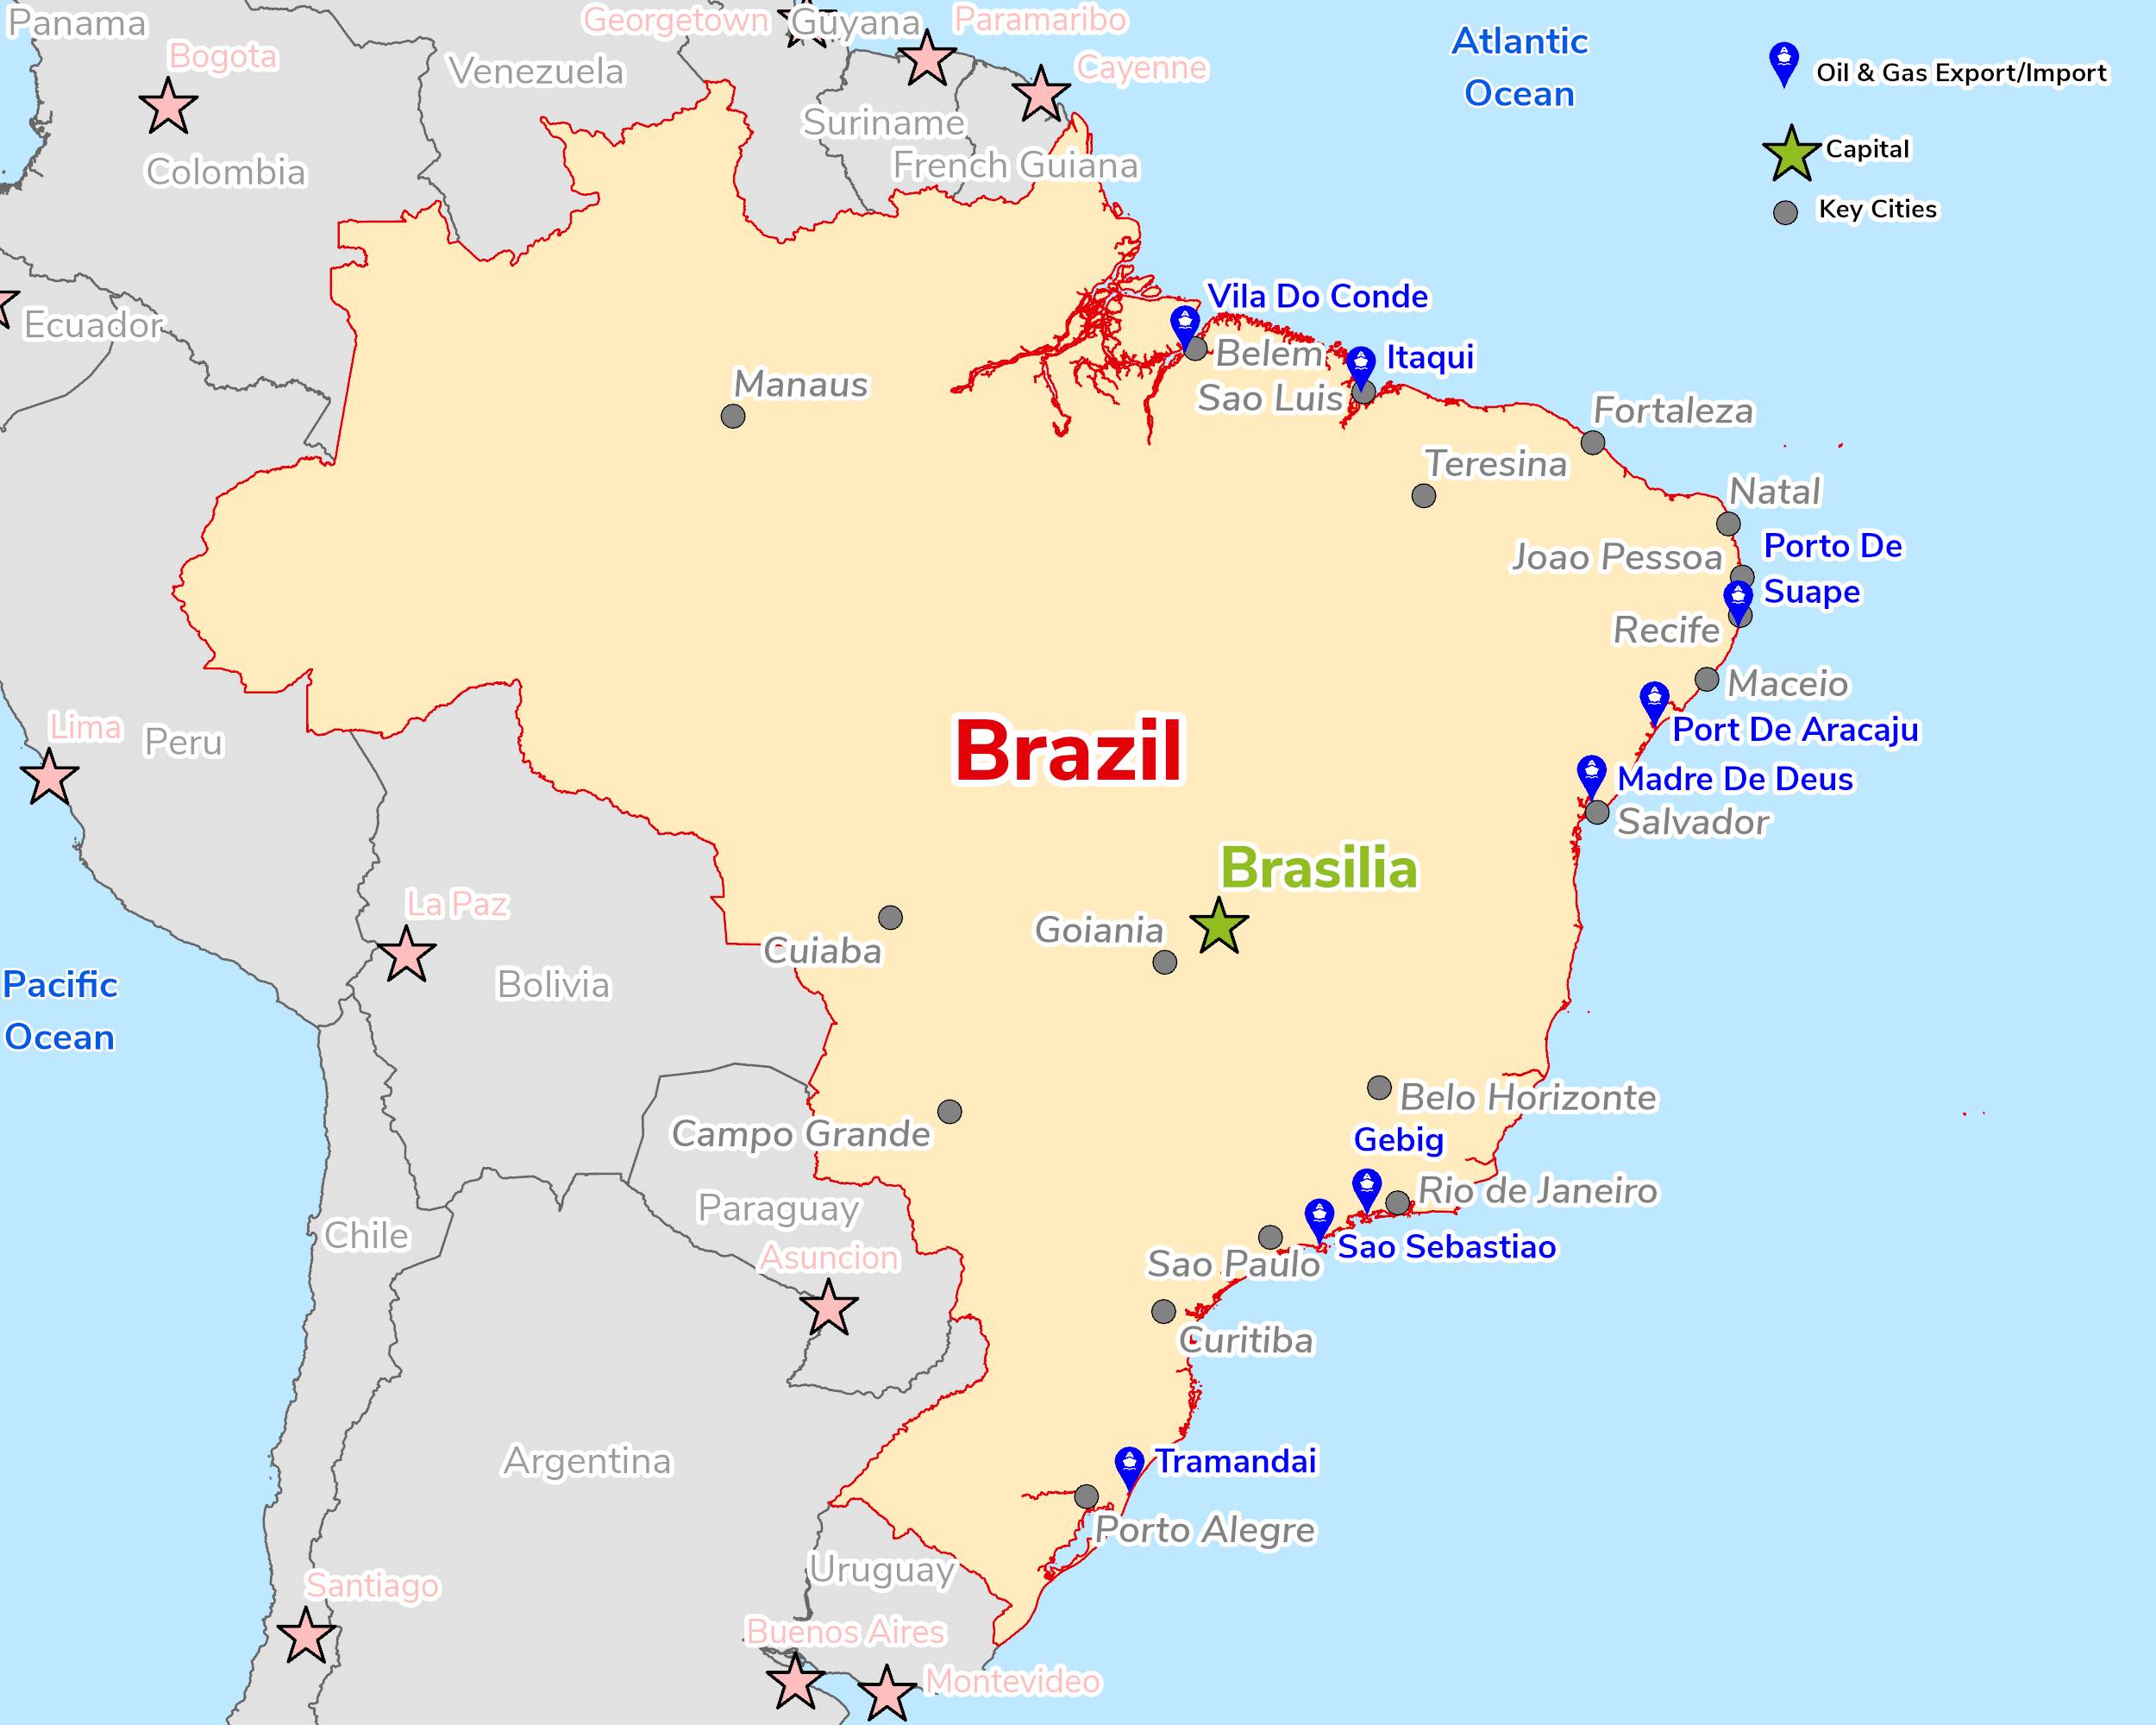
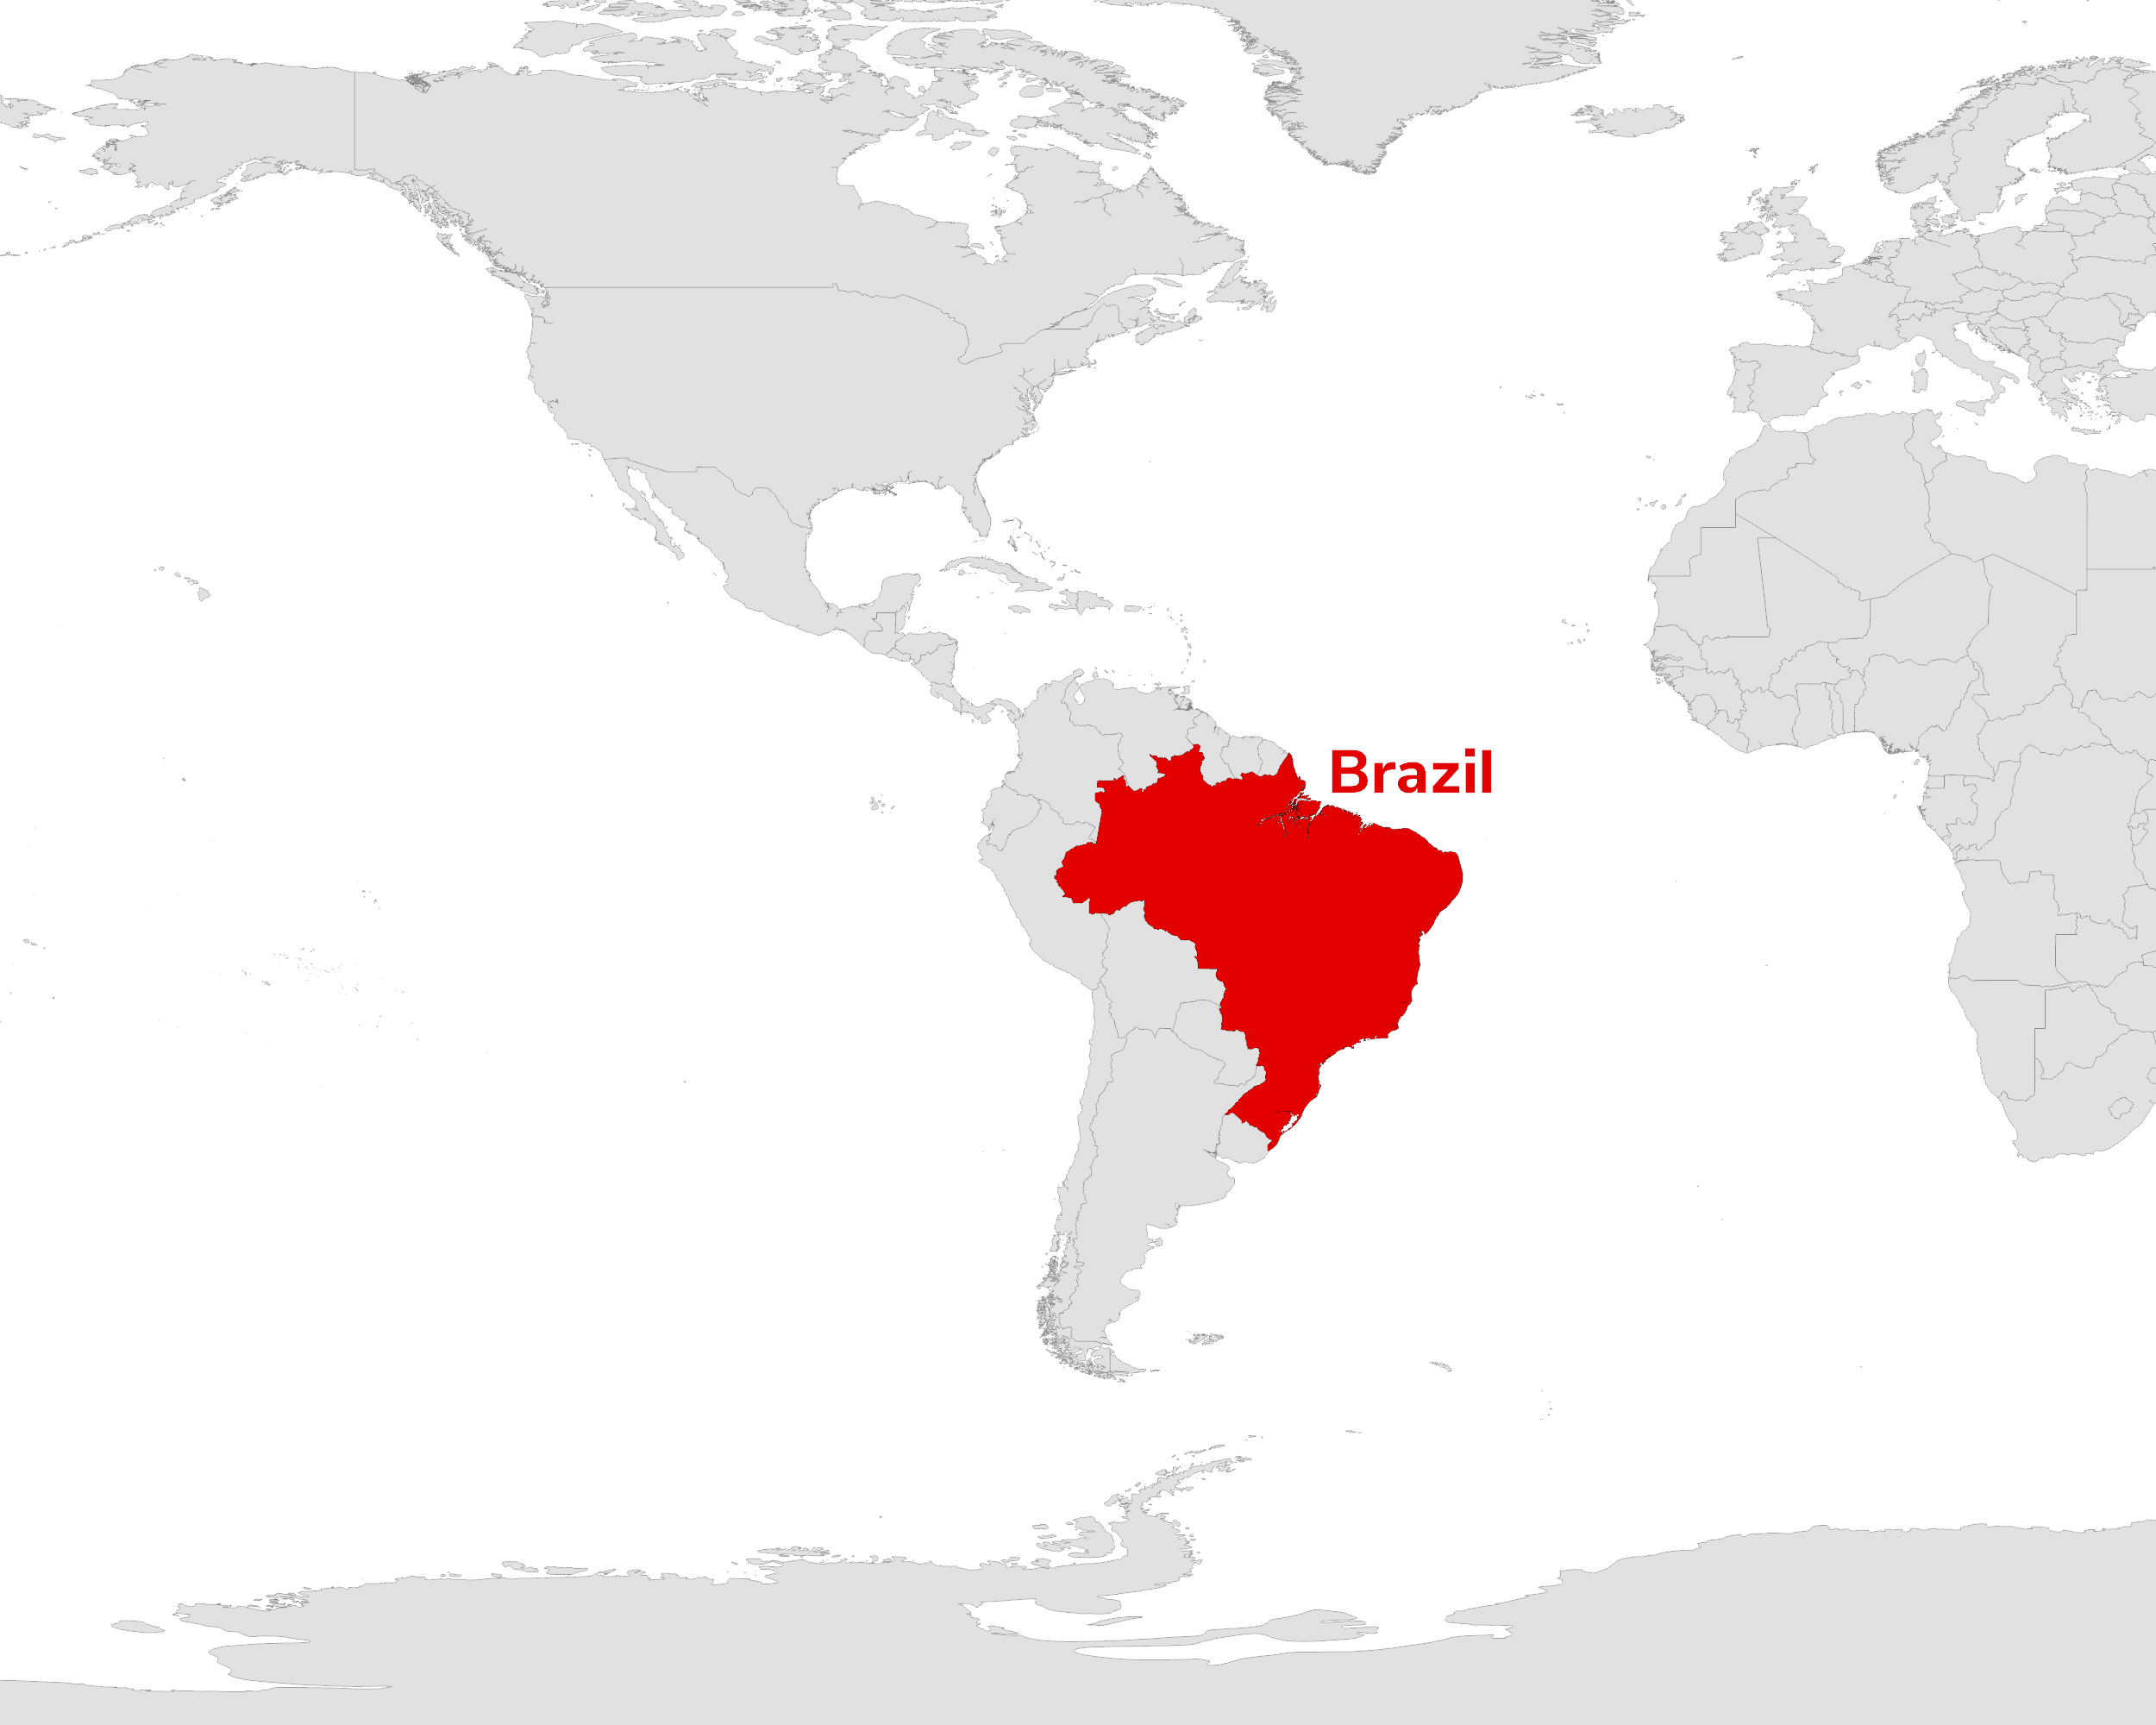
Eastern South America, bordering the Atlantic Ocean.
Multiple (PSC/Concession)
The Brazilian fiscal regime that applies to the oil and gas industry consists of corporate income tax (CIT) and Government and third-party takes. Government and third-party takes vary depending on the type of contract.
Brazil is a stable but polarised democracy holding its general election in October 2026, with fiscal credibility, high interest rates and US tariffs weighing on the outlook. US and UK guidance highlight a large, sophisticated market, but cite a notoriously complex tax system (a VAT reform is being phased in from 2026 to 2033), bureaucracy, local-content rules and legal uncertainty. The EIA identifies Brazil as Latin America's largest oil producer, with growth driven by Petrobras-operated pre-salt fields and FPSO additions. In October 2025 Petrobras received a licence to drill in the frontier Equatorial Margin (Foz do Amazonas), and the ANP's permanent-offer rounds continue to attract IOCs.
Source: ESRI, Heritage Index, HMG Foreign & Commonwealth Office, US Department of State, International Trade Administration, International Law Review, Ernst & Young, Wood Makenzie & OGA data.

© 2024 Oil & Gas Advisors Limited
Website by Rugby Web Design