5.000
%
Neutral
80
mm boe
0
%
Guyana remains at the top of the industry's agenda, with ExxonMobil's Stabroek block producing over 900,000 b/d and further developments sanctioned. The Venezuelan threat to the Essequibo region has receded, although the 2023 PSA terms for new blocks are tougher and local-content requirements are growing. Outlook amended from Neutral because the reduced Venezuelan threat and continued growth have strengthened the investment case. Outlook: Positive. Risk premia lowered from 6.25% to 5%.
October 8, 2026
Americas - South
mm bbl
bcf
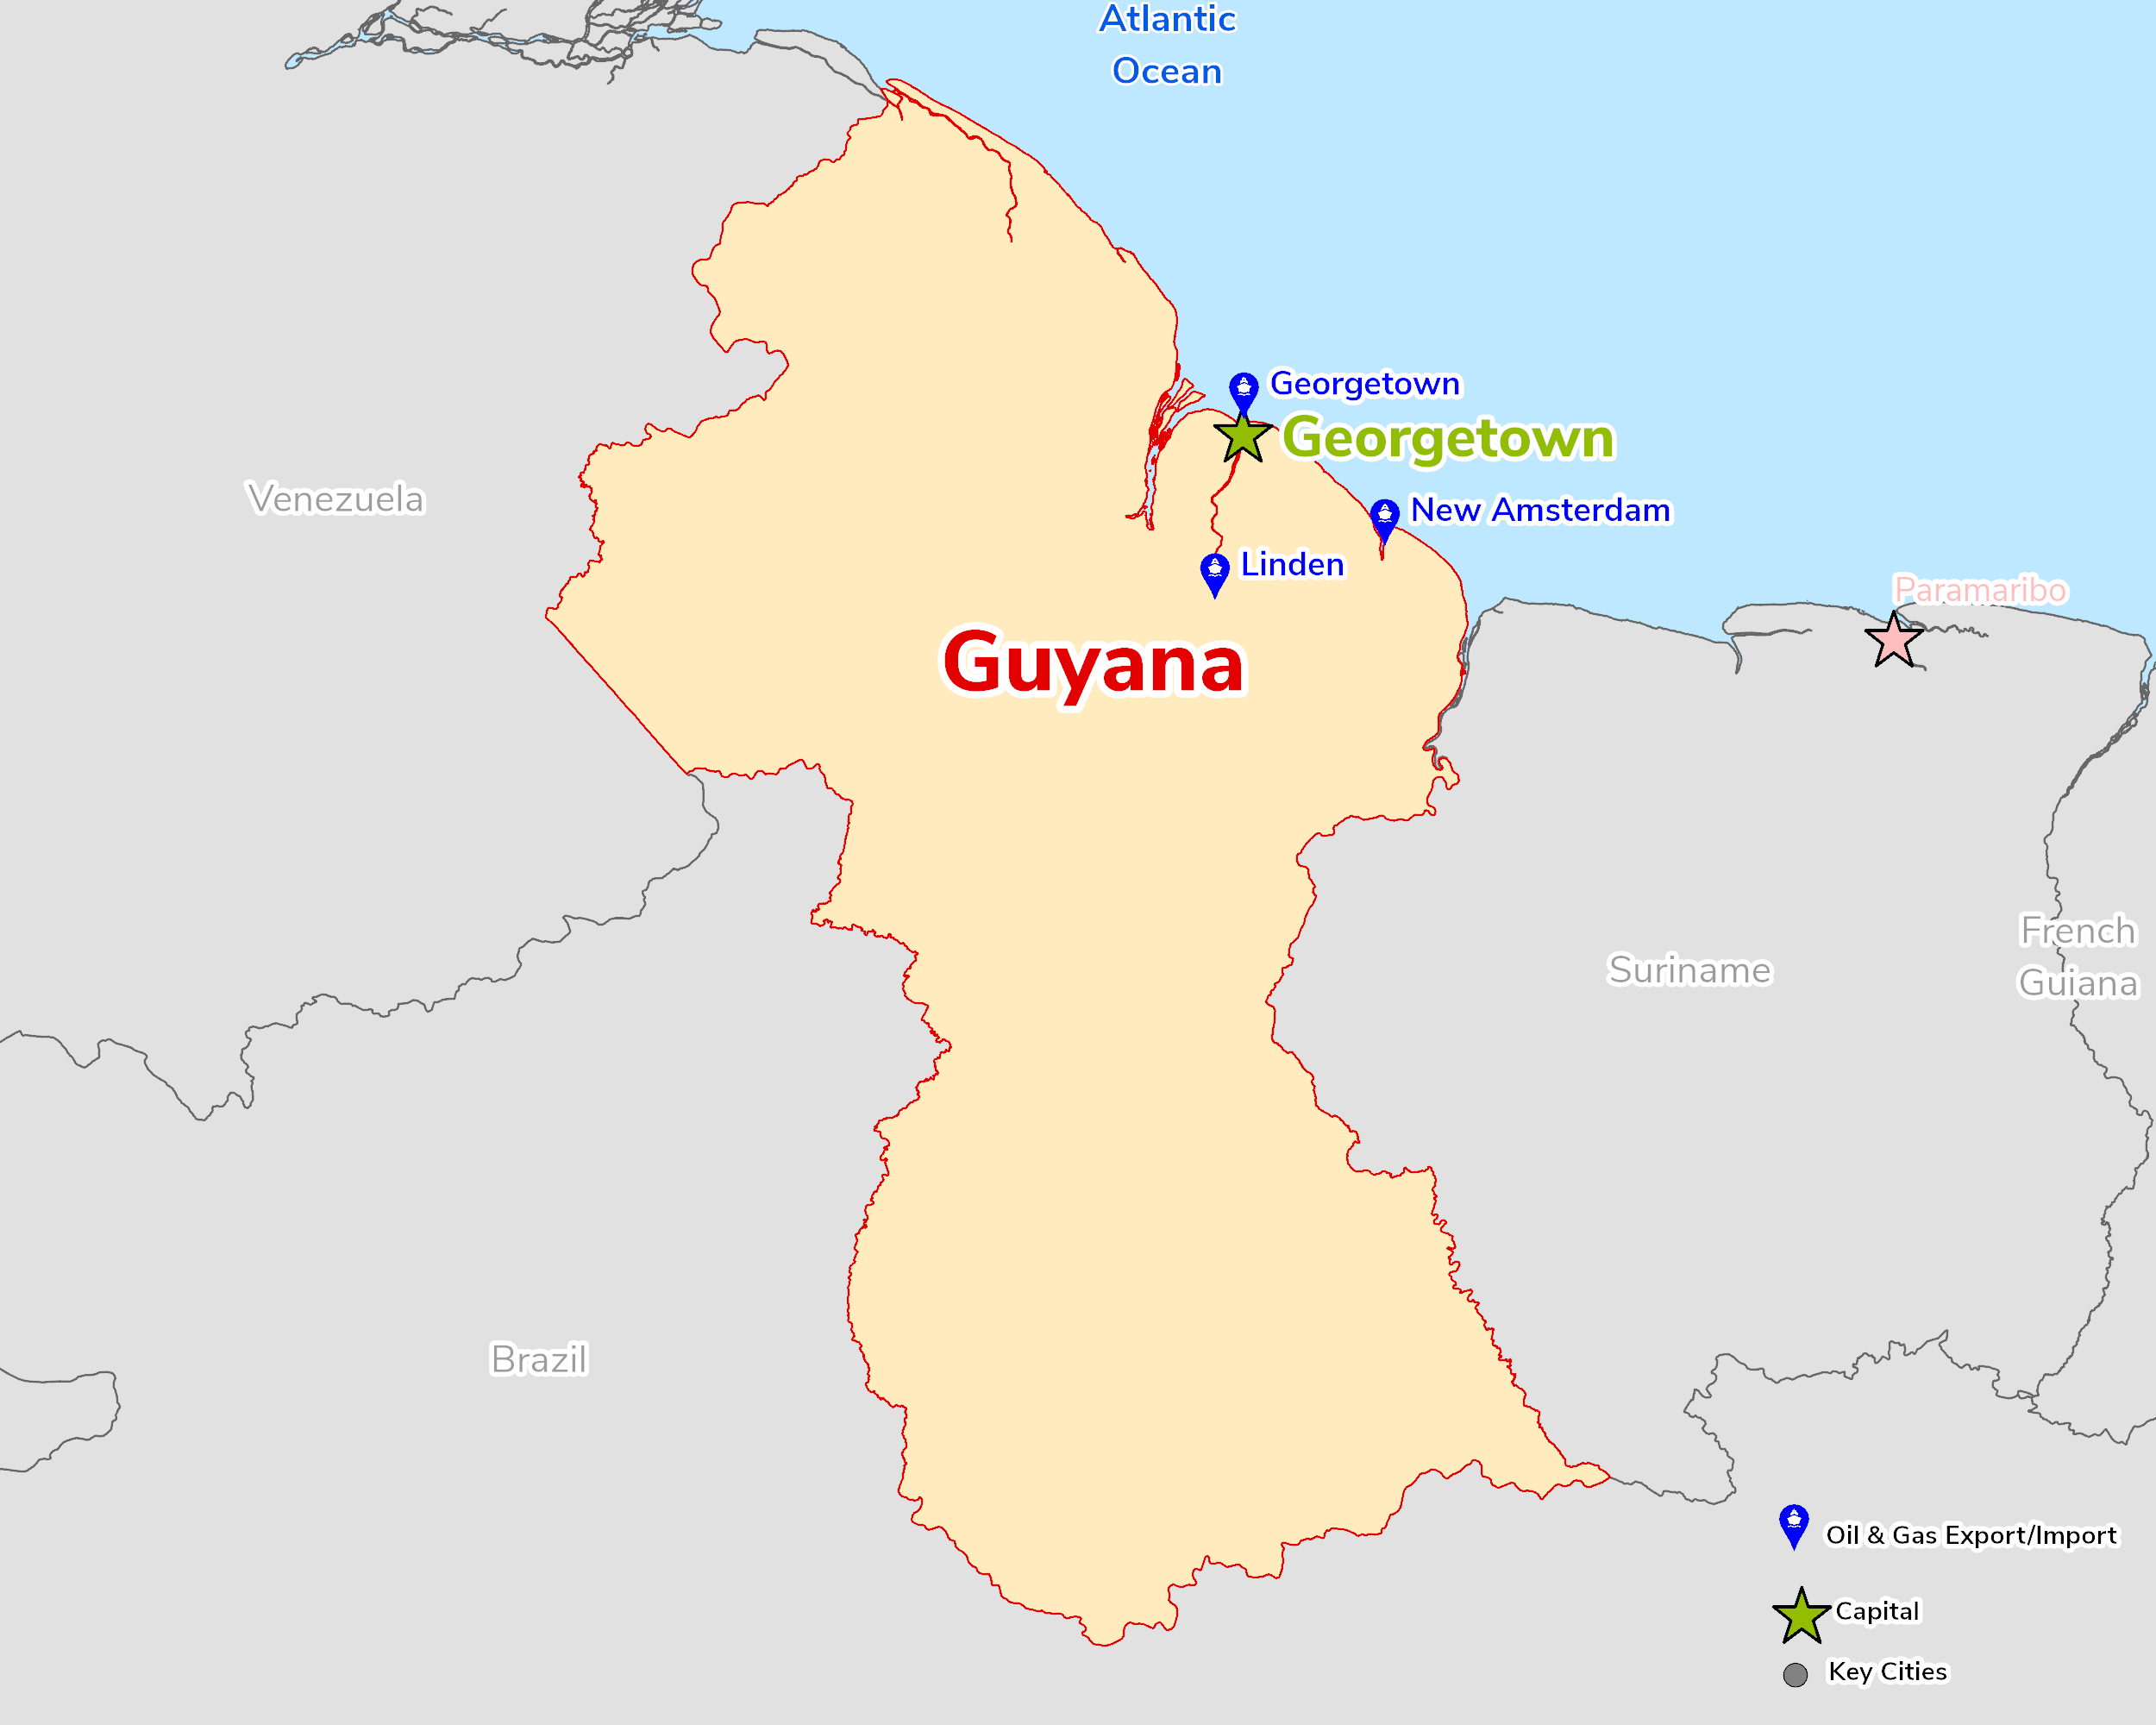
Northern South America, bordering the North Atlantic Ocean, between Suriname and Venezuela.
PSC/PSA
Production sharing regime. The 2016 Stabroek PSA carries a 2% royalty, a 75% cost recovery ceiling and a 50:50 profit split, with the contractor's income tax paid by the government. The 2023 model PSA, used for the 2022–23 licensing round awards and to apply to any new production outside Stabroek, raises the royalty to 10%, cuts cost recovery to 65%, keeps the 50:50 split, introduces a 10% corporate tax paid by the contractor and sets signature bonuses of US$10m (shallow water) to US$20m (deep water) per block. The Petroleum Activities Act 2023 replaced the 1986 Act.
President Irfaan Ali was re-elected in September 2025, and Guyana is one of the world's fastest-growing economies. Venezuela's claim to the Essequibo region, before the ICJ, remains the main geopolitical risk. US and UK guidance cite capacity constraints, corruption concerns, the 2021 local-content law and pressure on infrastructure and skills. The EIA notes that output from ExxonMobil's Stabroek block (with Chevron following its acquisition of Hess) rose to around 900,000 b/d in 2025 with Yellowtail, with further FPSOs sanctioned and the gas-to-energy project under way.
Source: ESRI, Heritage Index, HMG Foreign & Commonwealth Office, US Department of State, International Trade Administration, International Law Review, Ernst & Young, Wood Makenzie & OGA data.

© 2024 Oil & Gas Advisors Limited
Website by Rugby Web Design