6.875
%
Neutral
65
mm boe
3
%
Jordan remains under-explored, and the lack of meaningful conventional targets means it is unlikely to gain traction in the near to medium term. The Risha gas field is being expanded, but regional conflict weighs on sentiment. Outlook maintained because prospectivity remains limited. Outlook: Neutral. Risk premia unchanged at 6.875%.
October 7, 2026
Middle East
mm bbl
bcf
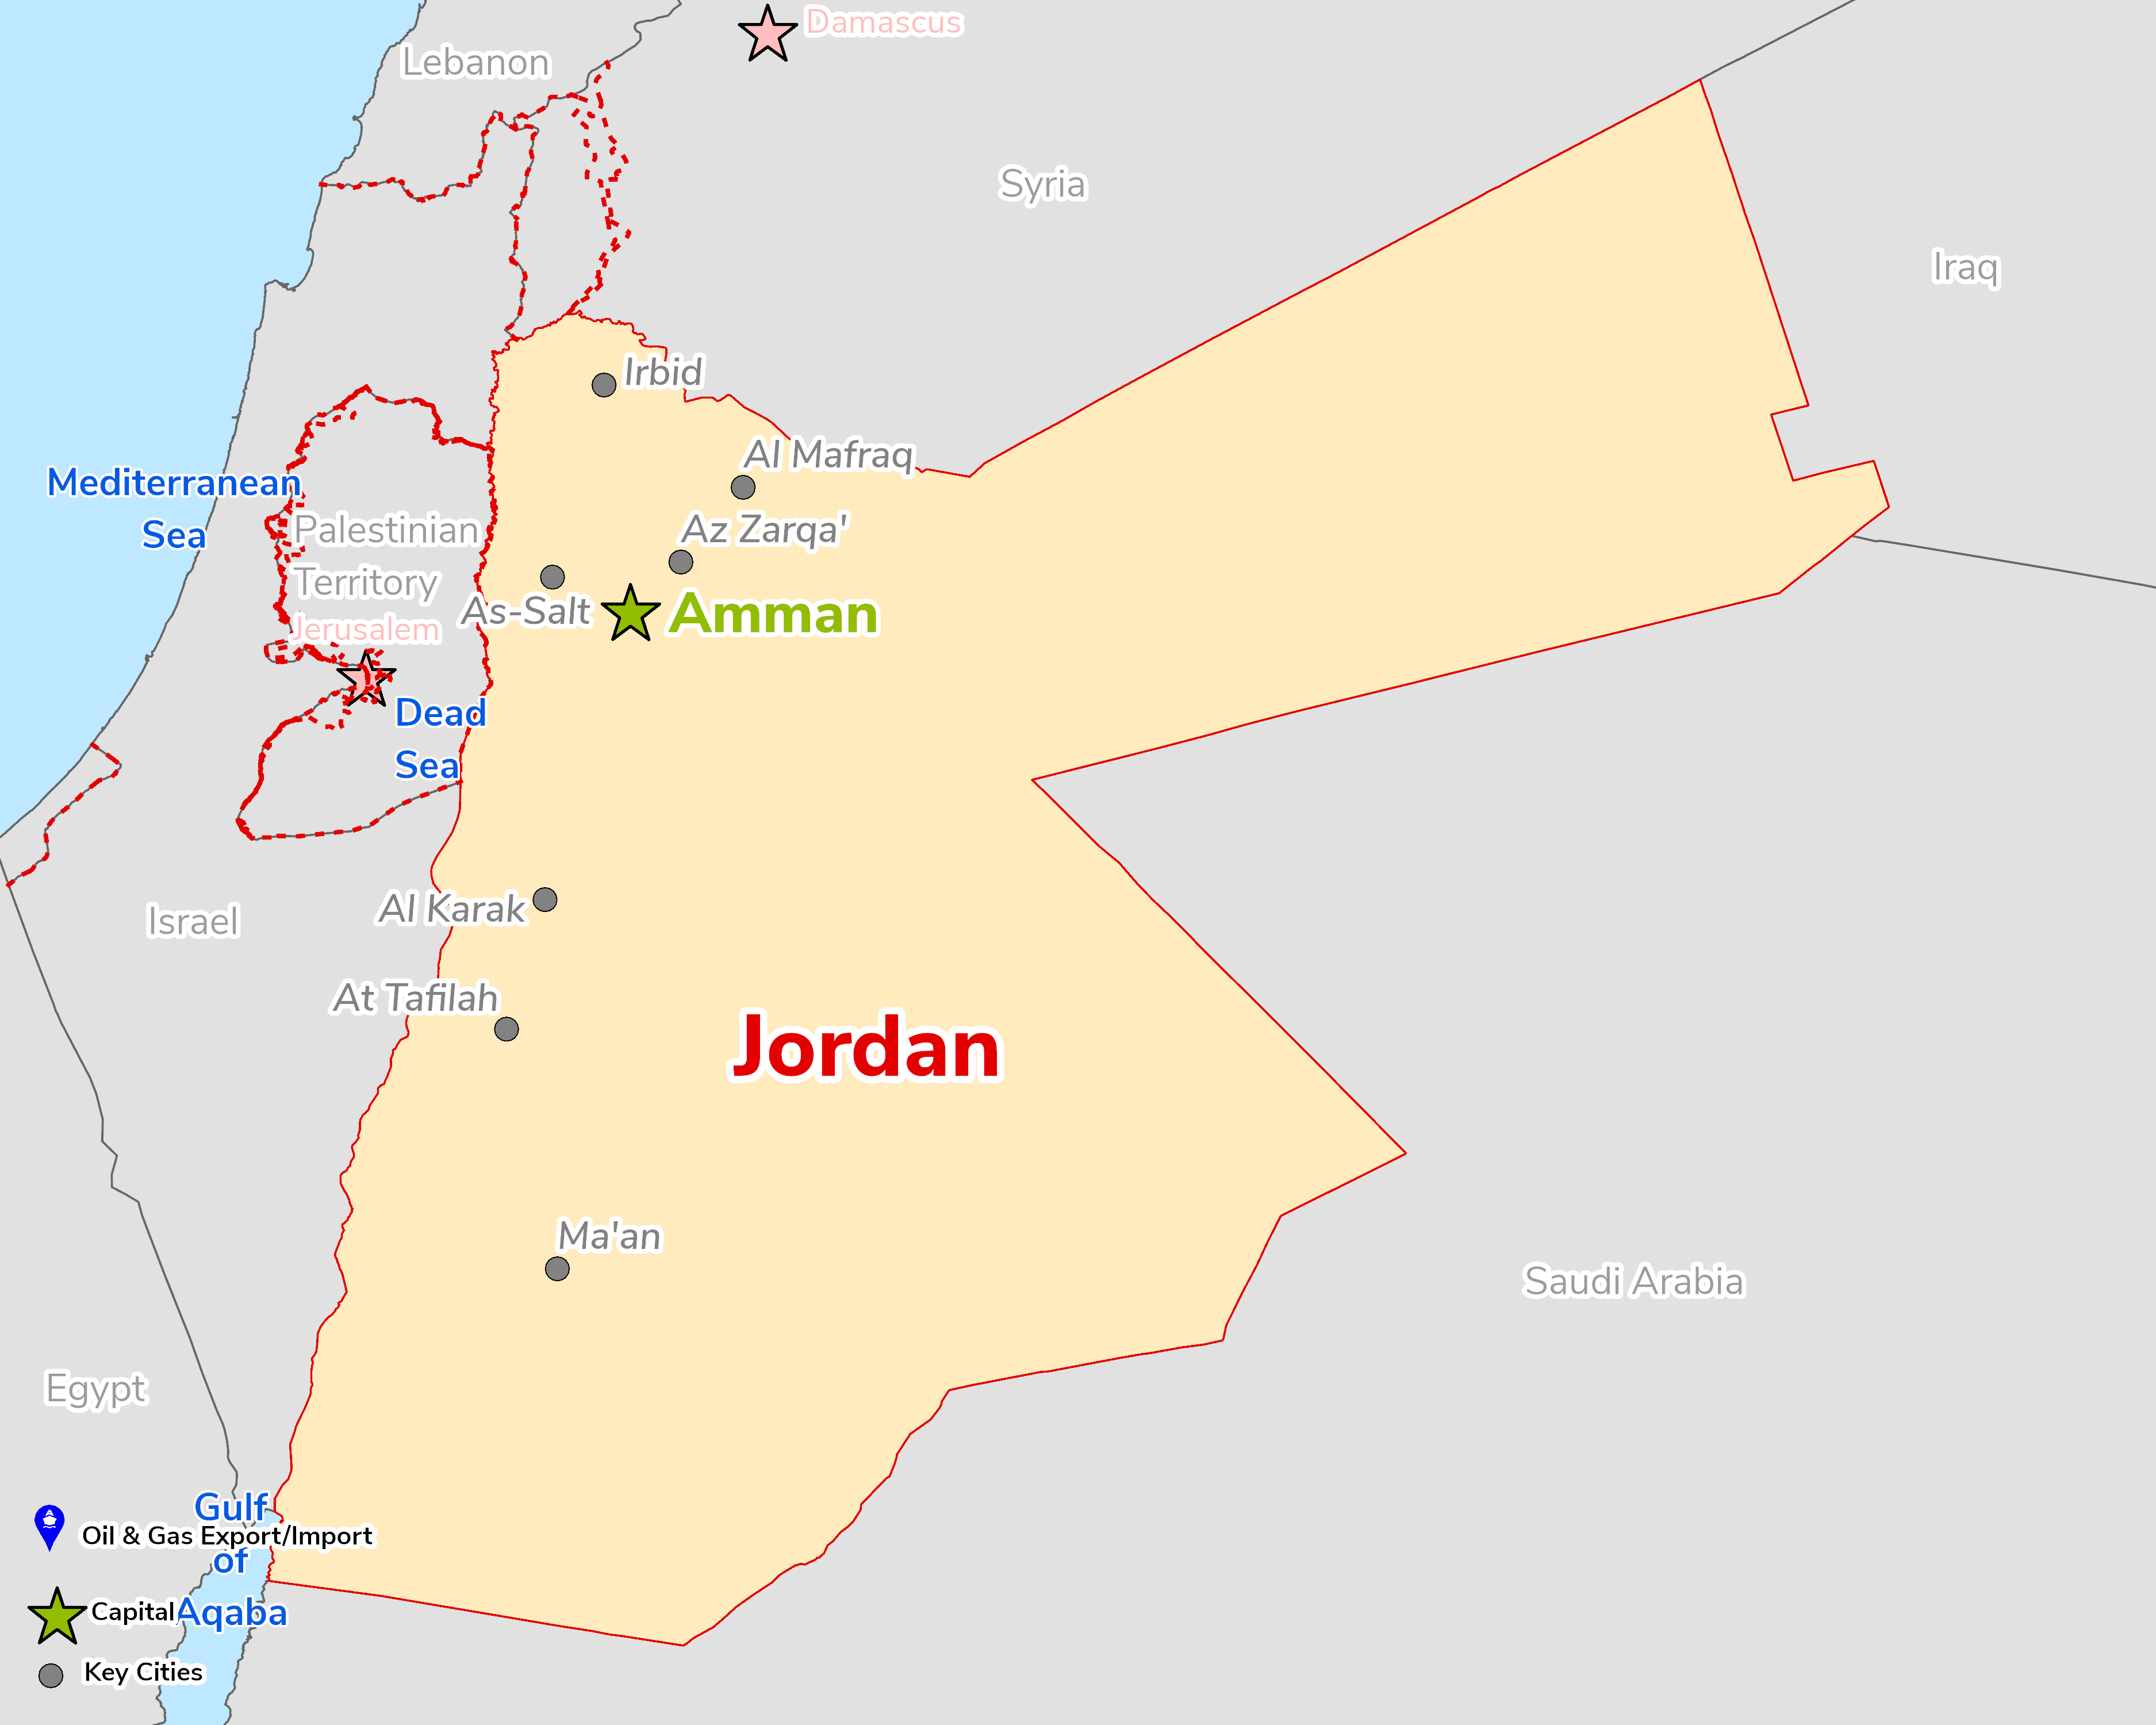
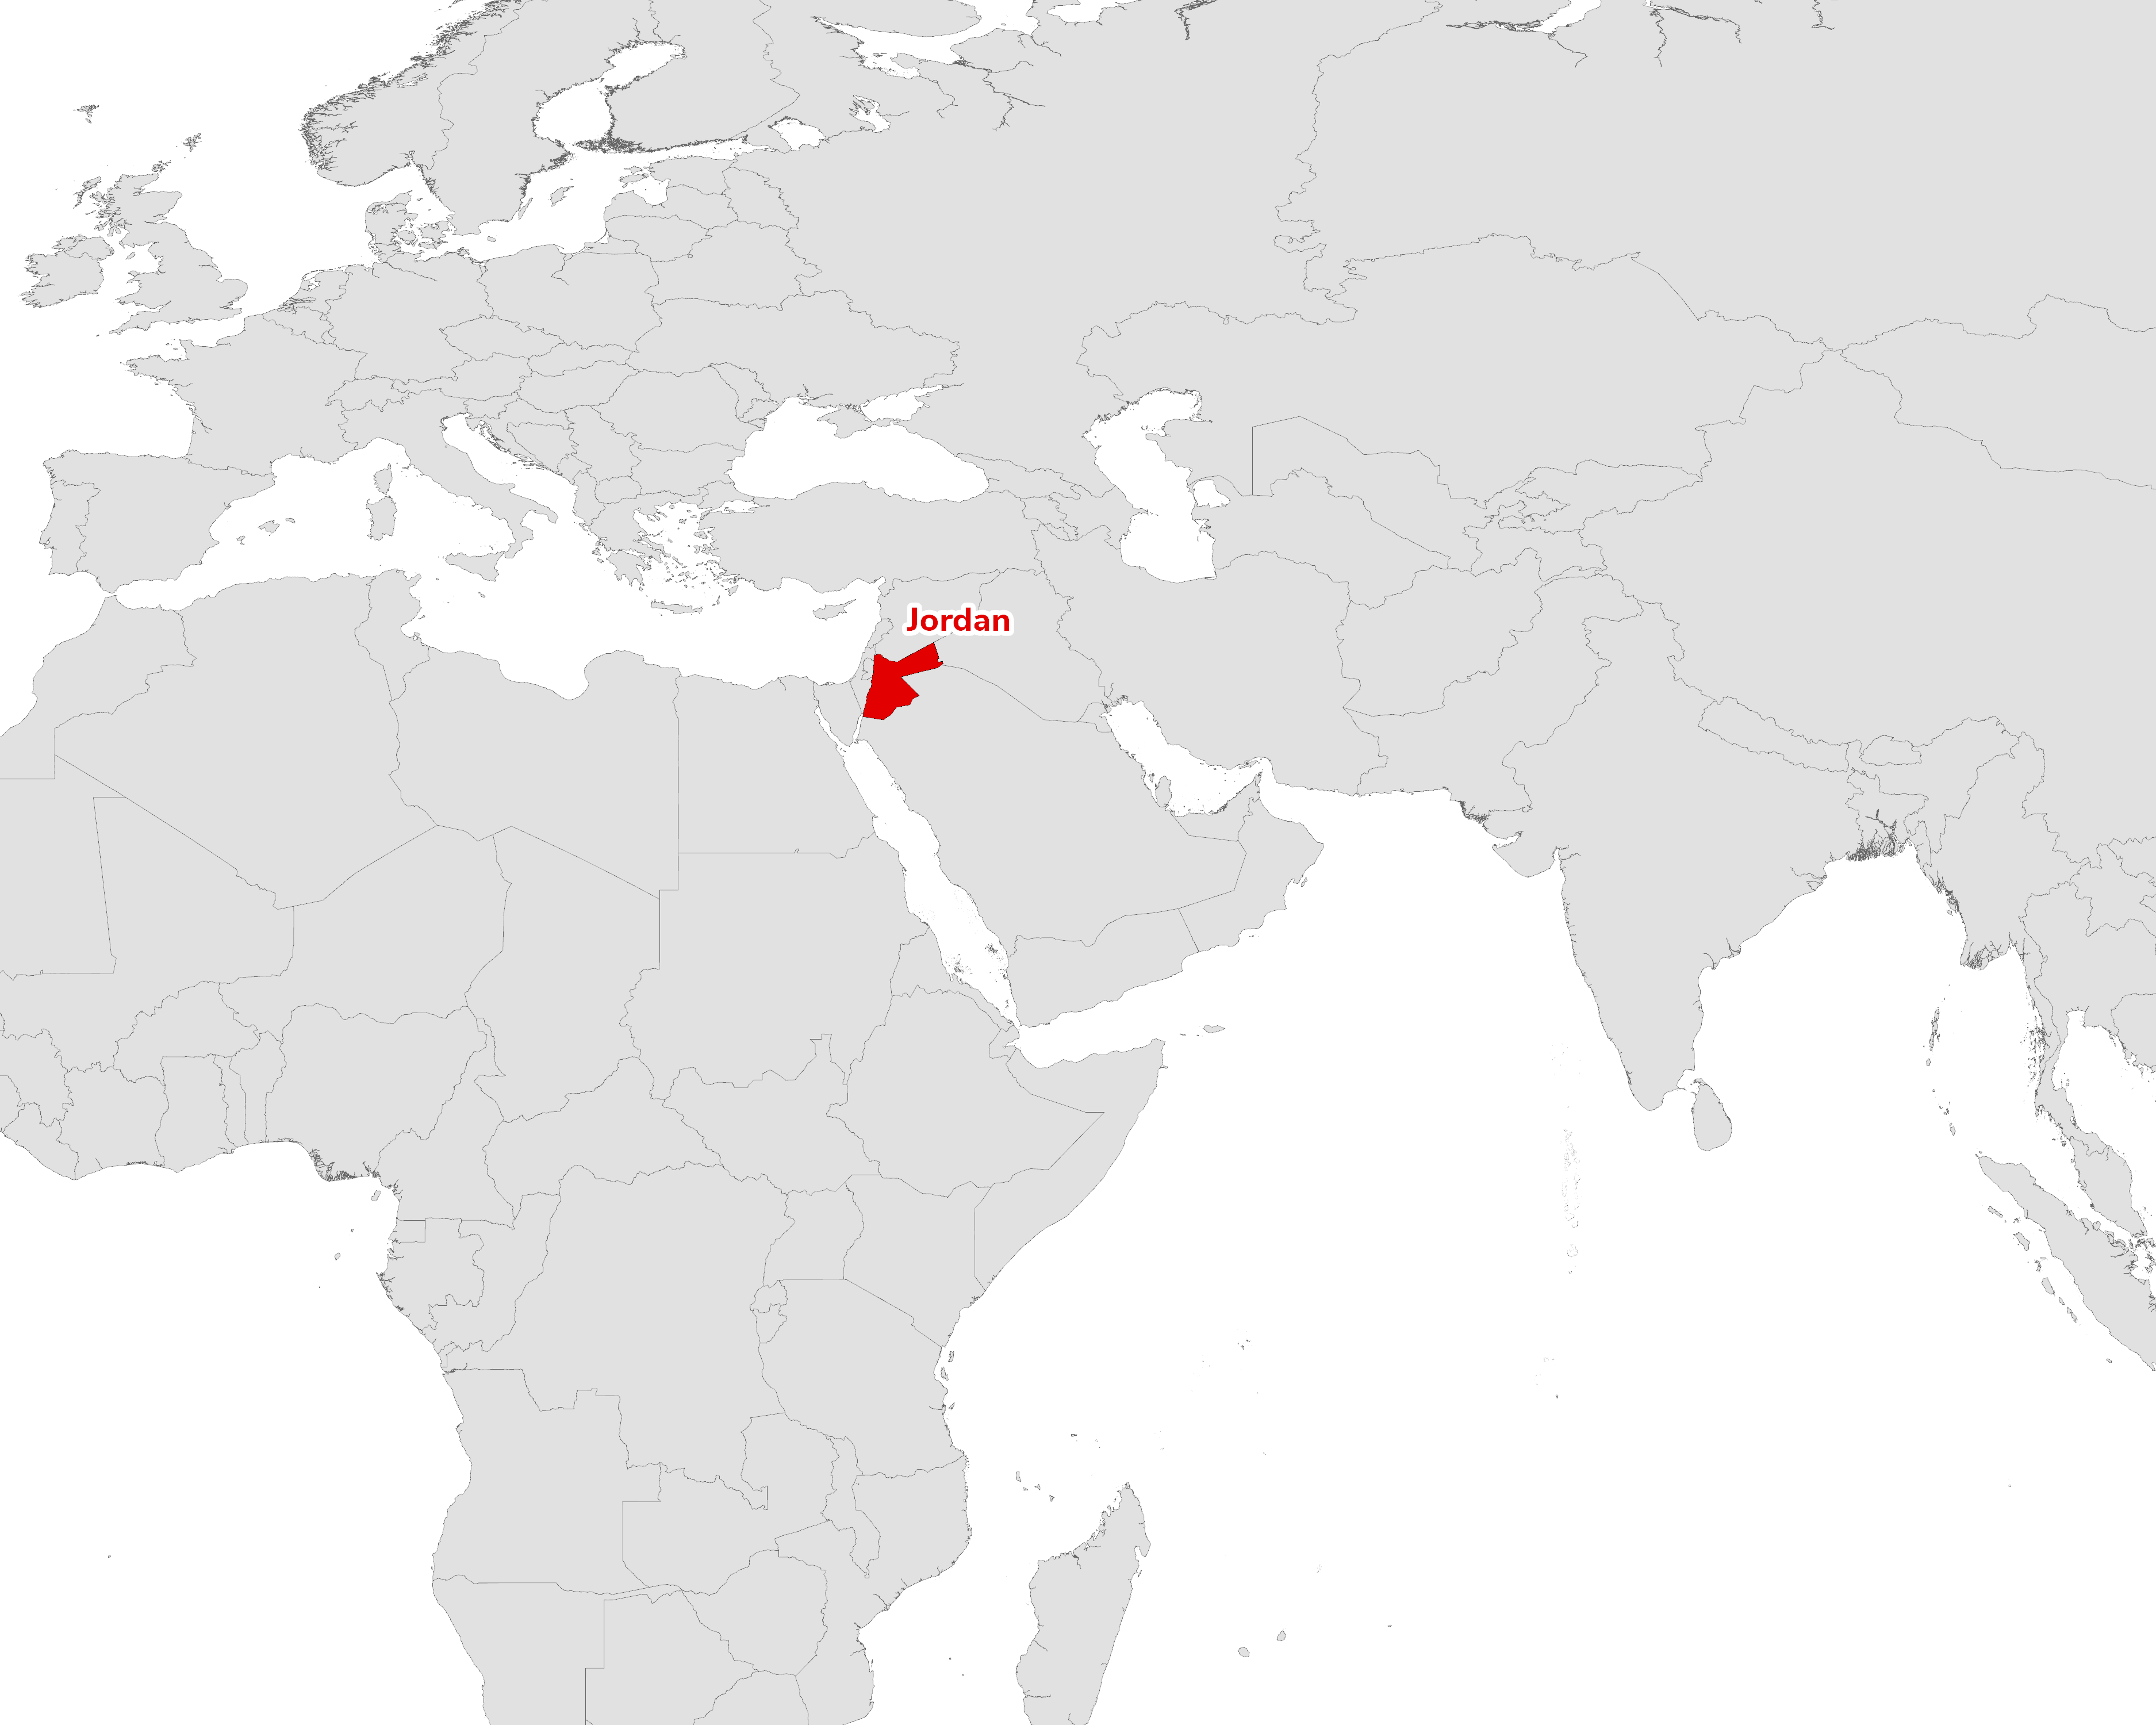
Middle East, northwest of Saudi Arabia, between Israel (to the west) and Iraq.
PSC/PSA
Simple Production Sharing Contract (PSC)-based fiscal regime, reflecting the frontier nature of Jordan’s onshore acreage. No royalty is payable. Profit oil splits are based on production rates, whilst corporate income tax is paid on the contractors' behalf by the government. There are no bonuses, rentals or fees.
Jordan is a stable US-aligned monarchy under King Abdullah II, but it is exposed to spillover from the Gaza and Syria conflicts and relies heavily on aid. US and UK guidance cite an IMF-backed reform programme, the US–Jordan FTA and qualified industrial zones, but note bureaucracy, high unemployment and fiscal constraints. Jordan imports almost all its energy, including Israeli gas from Leviathan and LNG via Aqaba. The Attarat oil-shale power plant is the subject of an arbitration dispute, while the state is expanding the small Risha gas field.
Source: ESRI, Heritage Index, HMG Foreign & Commonwealth Office, US Department of State, International Trade Administration, International Law Review, Ernst & Young, Wood Makenzie & OGA data.

© 2024 Oil & Gas Advisors Limited
Website by Rugby Web Design

