
1.625
%
Neutral
49
mm boe
82
%
Geopolitical turmoil has affected outside perceptions of the government, and lower oil prices have forced the scaling back of Vision 2030 projects. Independents' involvement in O&G is minimal, as Saudi Aramco dominates the sector, although gas development at Jafurah offers service and partnership opportunities. Outlook maintained because access remains limited and largely unaffected by recent changes. Outlook: Neutral. Risk premia unchanged at 1.625%.
October 7, 2026
Middle East
mm bbl
bcf
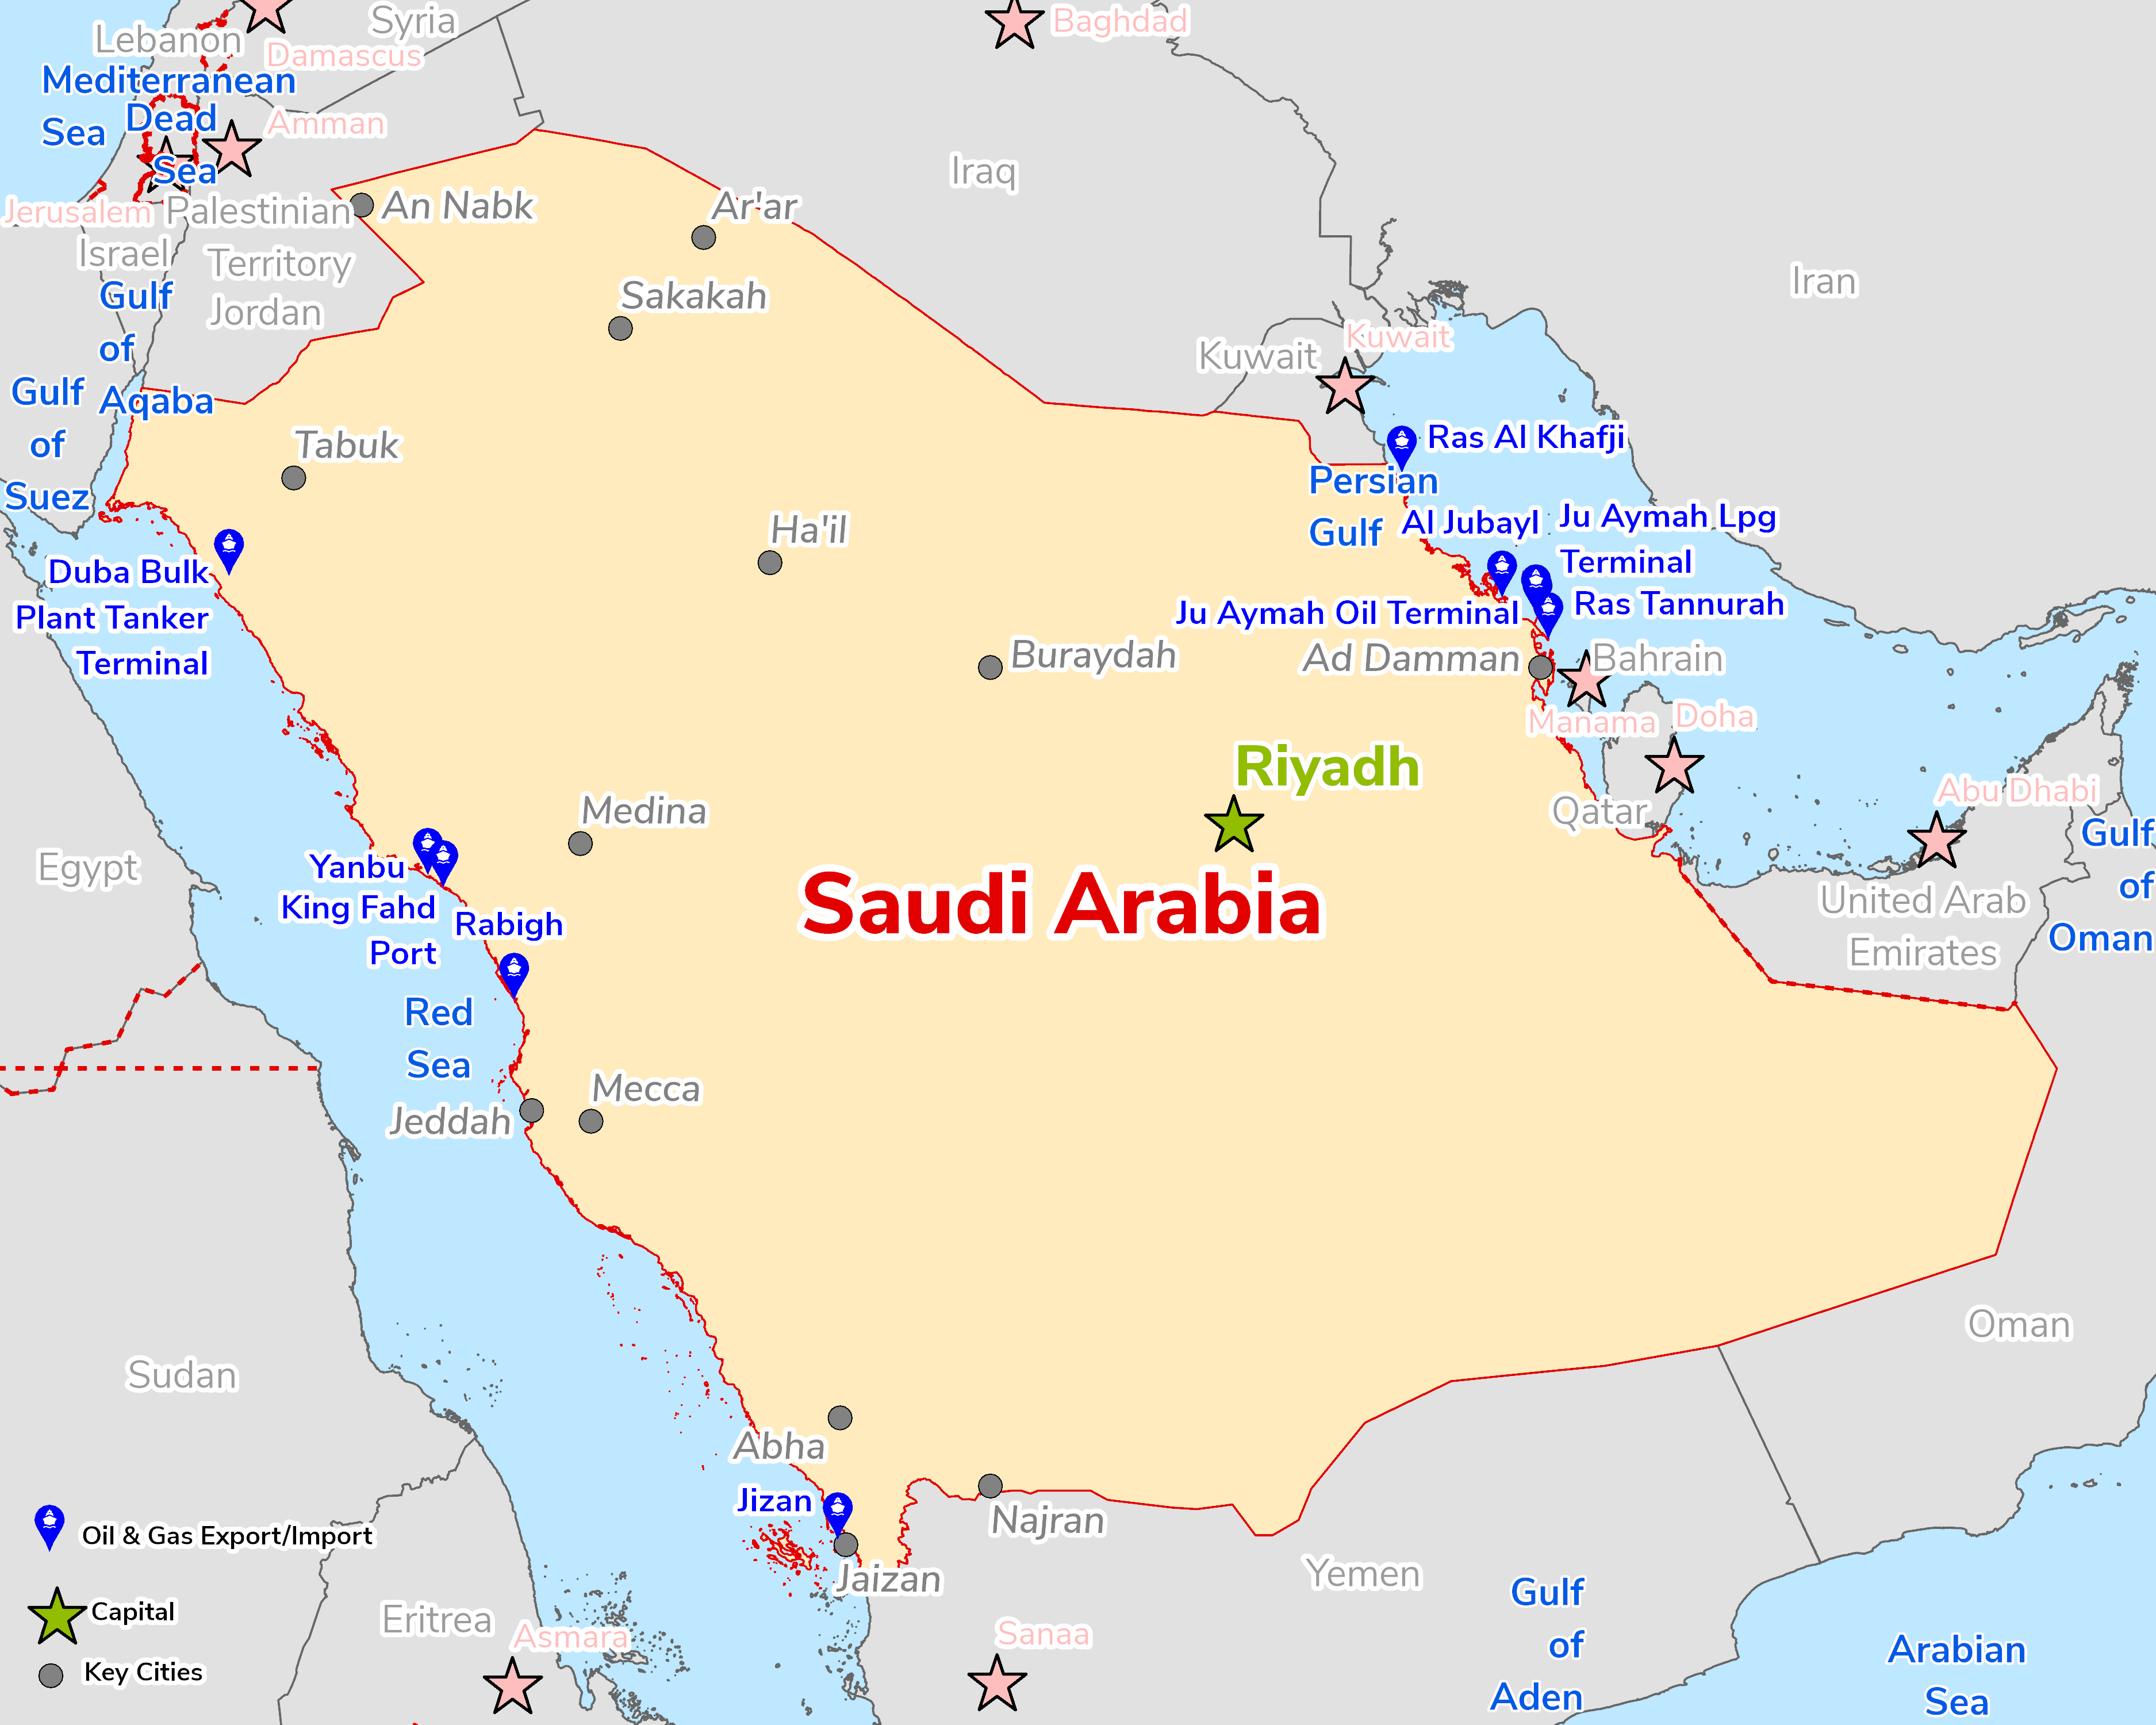
Middle East, bordering the Persian Gulf and the Red Sea, north of Yemen.
Concession
Concession-based fiscal regime, where concessions are exclusively and only applicable to new gas and condensate projects; any oil discoveries will revert to the owner- and operatorship of the national oil company (Saudi Aramco).
Crown Prince Mohammed bin Salman's government is stable, but lower oil prices and the OPEC+ decision to unwind cuts in 2025 have widened deficits and forced the scaling back of Vision 2030 giga-projects. US and UK guidance cite the 2025 Investment Law, liberalised FDI rules and large opportunities, but note the regional HQ rule, localisation and payment delays. The EIA notes that Saudi Arabia is the world's largest crude exporter. Saudi Aramco has abandoned its 13 million b/d capacity target, prioritising gas growth via Jafurah, which began production in 2025.
Source: ESRI, Heritage Index, HMG Foreign & Commonwealth Office, US Department of State, International Trade Administration, International Law Review, Ernst & Young, Wood Makenzie & OGA data.

© 2024 Oil & Gas Advisors Limited
Website by Rugby Web Design


